VÍ DỤ THỰC TẾ · RÀ SOÁT VĂN BẢN TRONG WORD
Thư của Chủ tịch được hiệu đính, sau đó cắt gọn thành phiên bản web 600 từ
Một nhân viên truyền thông tại ngân hàng cộng đồng đã nhận được báo cáo thường niên dưới dạng tệp Word. Họ yêu cầu hiệu đính bức thư của chủ tịch theo phong cách AP một cách nhẹ nhàng, không sửa đổi các con số, đoạn trích từ bức thư năm ngoái hoặc các bảng tài chính.
đã sửa lỗi bổ nghĩa lơ lửng, làm mượt các câu chữ gượng gạo và nối lại ba câu bị chia tách do quá trình chuyển đổi tệp, tất cả diễn ra trong cùng một tệp, đồng thời giữ nguyên mọi con số. Sau đó, nó đã rút gọn bức thư từ 1.093 từ xuống còn 600 từ cho bản web, viết các tỷ lệ phần trăm bằng chữ số và giữ nguyên vẹn phần kết luận.
1Tải lên: báo cáo thường niên của ngân hàng, dưới dạng tệp Word
Message From the Chairman
Dear Fellow Shareholders:
Fiscal 2026
Fiscal 2027
A Final Word
Sincerely,
Financial Highlights
- 1,093 → 600số từ trong thư sau yêu cầu 2
- 3các câu bị tách được nối lại
- 8các con số "phần trăm" được đổi thành %, giữ nguyên giá trị
- 0các chỉnh sửa bên ngoài thư
Mở các tệp thực tế
Đây là các tệp thực tế từ quá trình chạy. Tải xuống và mở chúng trong Word.
Nguồn của tệp: Provident Financial Holdings, Inc., Báo cáo thường niên gửi cổ đông năm 2026, được nộp cho SEC dưới dạng Phụ lục 13 của Mẫu 10-K. Đây là hồ sơ công khai; văn bản thuộc sở hữu của công ty.
01 · TỆP BAN ĐẦU
Báo cáo thường niên 9 trang, thư ở trang 2
Tệp này là báo cáo thường niên gửi cổ đông của một ngân hàng niêm yết nhỏ: trang bìa, thư từ chủ tịch, sau đó là các bảng Financial Highlights, thông tin cổ đông, hội đồng quản trị và danh sách chi nhánh. Chín trang và sáu bảng trong một tệp Word.
Chúng tôi đã tạo tệp Word này từ hồ sơ SEC công khai (một trang web) bằng LibreOffice. Quá trình chuyển đổi đã làm tách ba câu thành hai đoạn mỗi câu, một lỗi phổ biến khi một trang web trở thành tệp Word. Yêu cầu đã nhập nêu rõ cả ba vị trí.
02 · YÊU CẦU 1
"Hiệu đính bức thư theo phong cách AP và chỉ chỉnh sửa nhẹ"
Nội dung nhân viên truyền thông đã nhập
Please proofread the 'Message From the Chairman' (from 'Dear Fellow Shareholders:' down to Craig Blunden's signature block) with tracked changes, AP style.

- Fix grammar, punctuation and awkward phrasing, but keep the edits light.
- Don't change any figures or the meaning. Leave the way numbers are written ('61 percent', 'one percent') alone for now.
- The quotation from last year's letter in the first paragraph ('… the market is expecting … California real estate market.') must stay word for word.
- Three sentences were split into two paragraphs when the file was converted: after 'disciplined,', after 'this approach is the', and after 'the year ahead and beyond,'. Join each back into one paragraph.
- Don't touch the Financial Highlights tables or anything after the letter.
Những gì đã làm
- Đã chỉnh sửa bức thư bên trong tệp Word được tải lên. Văn bản của tất cả các trang khác được giữ nguyên.
- Đã sửa lỗi bổ nghĩa lơ lửng: "As the largest independent community bank headquartered in Riverside County, I am proud" nay thành "we are proud", ở đây và trong câu tiếp theo.
- Đã thực hiện các chỉnh sửa nhẹ theo phong cách AP: "high-cost markets" có dấu gạch nối, dấu gạch em có khoảng trắng trong "fiscal 2026 — our eighth consecutive year", và "remains constant" thay vì "remains a constant".
- Đã làm mượt các câu chữ gượng gạo, chẳng hạn như "Last year, I said" thay cho "Last year, I described that", và bỏ bớt một số từ mà các câu không cần thiết.
- Đã nối ba câu bị tách trở lại thành một đoạn cho mỗi câu.
- Giữ nguyên đoạn trích từ bức thư năm ngoái, mọi con số và cách viết của từng con số hoàn toàn như ban đầu.
Yêu cầu đã nhập có đề nghị theo dõi thay đổi, nhưng đã viết các chỉnh sửa thẳng vào tệp, do đó phần đánh dấu đỏ bên dưới xuất phát từ tính năng “Tạo báo cáo theo dõi thay đổi” của riêng , chạy trên các tệp trước và sau khi sửa.
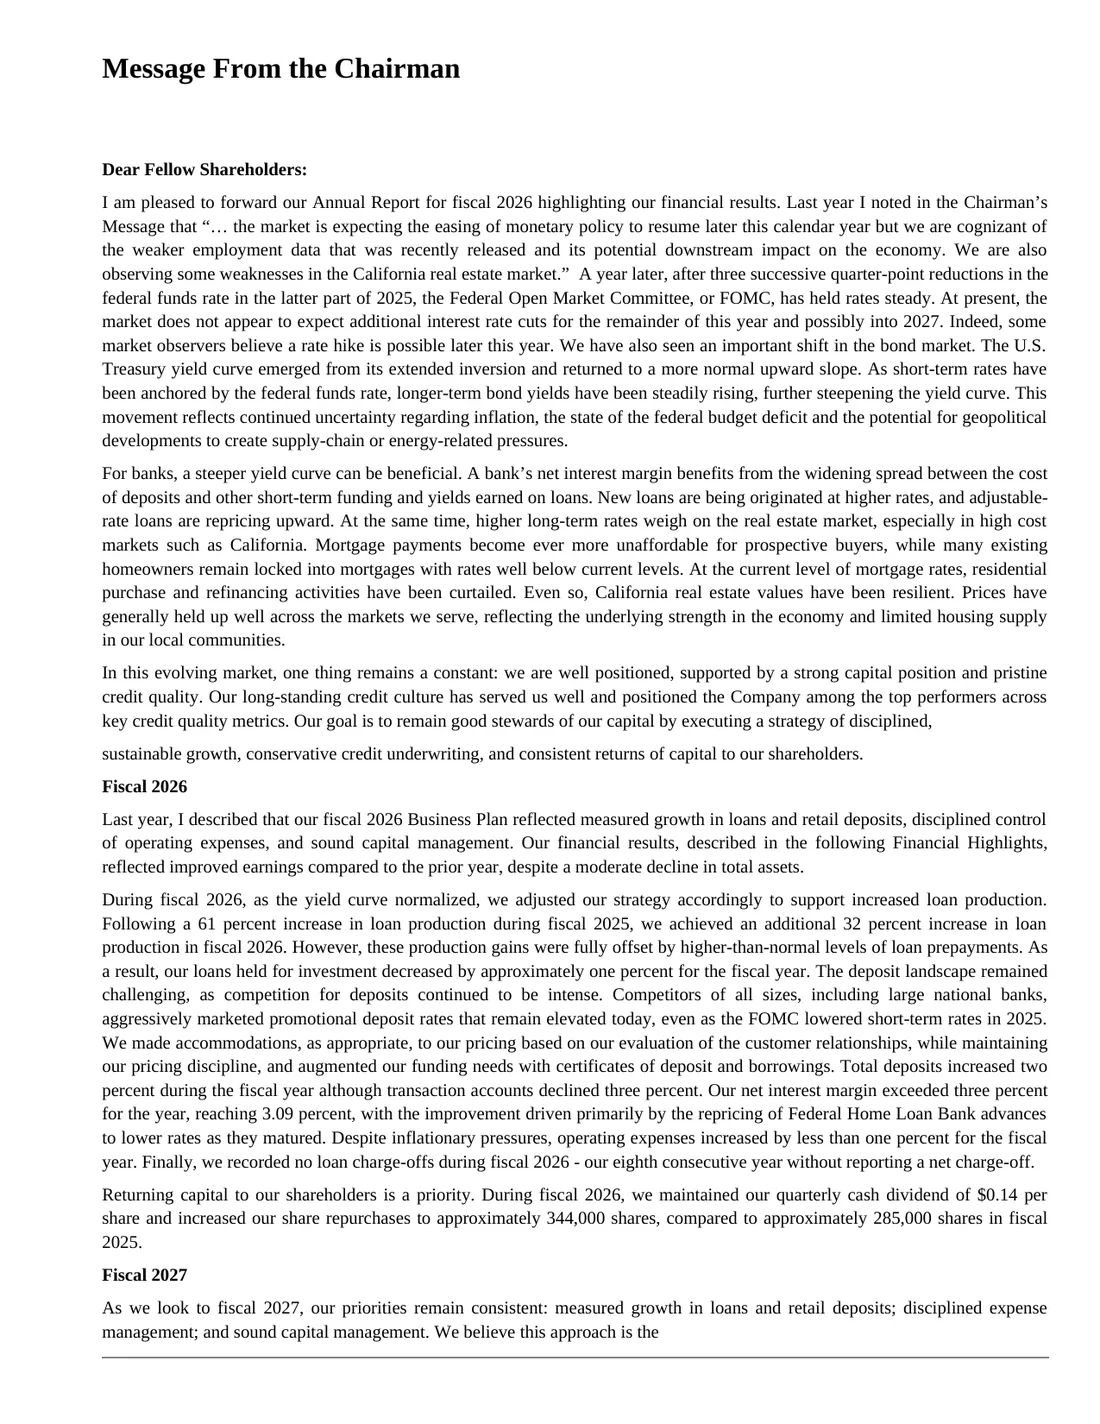
Message From the Chairman
Dear Fellow Shareholders:
I am pleased to forward our Annual Report for fiscal 2026 highlighting our financial results. Last year I noted in the Chairman’s Message that “… the market is expecting the easing of monetary policy to resume later this calendar year but we are cognizant of the weaker employment data that was recently released and its potential downstream impact on the economy. We are also observing some weaknesses in the California real estate market.” A year later, after three successive quarter-point reductions in the federal funds rate in the latter part of 2025, the Federal Open Market Committee, or FOMC, has held rates steady. At present, the market does not appear to expect additional interest rate cuts for the remainder of this year and possibly into 2027. Indeed, some market observers believe a rate hike is possible later this year. We have also seen an important shift in the bond market. The U.S. Treasury yield curve emerged from its extended inversion and returned to a more normal upward slope. As short-term rates have been anchored by the federal funds rate, longer-term bond yields have been steadily rising, further steepening the yield curve. This movement reflects continued uncertainty regarding inflation, the state of the federal budget deficit and the potential for geopolitical developments to create supply-chain or energy-related pressures.
For banks, a steeper yield curve can be beneficial. A bank’s net interest margin benefits from the widening spread between the cost of deposits and other short-term funding and yields earned on loans. New loans are being originated at higher rates, and adjustable-rate loans are repricing upward. At the same time, higher long-term rates weigh on the real estate market, especially in high -cost markets such as California. Mortgage payments have become ever moreincreasingly unaffordable for prospective buyers, while many existing homeowners remain locked into mortgages with rates well below current levels. At the current level of mortgage rates, residential purchase and refinancing activities have been curtailed. Even so, California real estate values have been resilient. Prices have generally held up well across the markets we serve, reflecting the underlying strength in the economy and limited housing supply in our local communities.
In this evolving market, one thing remains a constant: we are well positioned, supported by a strong capital position and pristine credit quality. Our long-standing credit culture has served us well and positioned the Company among the top performers across key credit quality metrics. Our goal is to remain good stewards of our capital by executing a strategy of disciplined, 
sustainable growth, conservative credit underwriting, and consistent returns of capital to our shareholders.
Fiscal 2026
Last year, I described thatsaid our fiscal 2026 Business Plan reflected measured growth in loans and retail deposits, disciplined control of operating expenses, and sound capital management. Our financial results, described in the following Financial Highlights, reflected improved earnings compared to the prior year, despite a moderate decline in total assets.
During fiscal 2026, as the yield curve normalized, we adjusted our strategy accordingly to support increased loan production. Following a 61 percent increase in loan production during fiscal 2025, we achieved an additional 32 percent increase in loan production in fiscal 2026. However, these production gains were fully offset by higher-than-normal levels of loan prepayments. As a result, our loans held for investment decreased by approximately one percent for the fiscal year. The deposit landscape remained challenging, as competition for deposits continued to be intense. Competitors of all sizes, including large national banks, aggressively marketed promotional deposit rates that remain elevated today, even as the FOMC lowered short-term rates in 2025. We made accommodations, as appropriate, to our pricing based on our evaluation of the customer relationships, while maintaining our pricing discipline, and augmented our funding needs with certificates of deposit and borrowings. Total deposits increased two percent during the fiscal year although transaction accounts declined three percent. Our net interest margin exceeded three percent for the year, reaching 3.09 percent, with the improvement driven primarily by the repricing of Federal Home Loan Bank advances to lower rates as they matured. Despite inflationary pressures, operating expenses increased by less than one percent for the fiscal year. Finally, we recorded no loan charge-offs during fiscal 2026 -— our eighth consecutive year without reporting a net charge-off.
Returning capital to our shareholders is a priority. During fiscal 2026, we maintained our quarterly cash dividend of $0.14 per share and increased our share repurchases to approximately 344,000 shares, compared to approximately 285,000 shares in fiscal 2025.
Fiscal 2027
As we look to fiscal 2027, our priorities remain consistent: measured growth in loans and retail deposits; disciplined expense management; and sound capital management. We believe this approach is the 
right course in an economy that continues to expand, while recognizing the need to remain cautious amid ongoing market and geopolitical uncertainties. We expect to continue returning capital to shareholders through dividends and share repurchases while maintaining sufficient capital to support our business strategy and withstand potential losses under adverse conditions. We remain committed to single-family residential, multi-family, and commercial real estate mortgage lending as our primary sources of asset growth and our retail branch network will continue to serve as the primary source of the Bank’s funding.
A Final Word
This year, Provident proudly celebrates the 70th anniversary of its founding, serving the great city of Riverside and its surrounding communities. As the largest independent community bank headquartered in Riverside County, I amwe are proud of our distinguished history as a trusted provider of banking services. Just as importantly, I amwe are proud of the commitment demonstrated throughout our organization to strengthen the communities we serve through volunteer service, charitable support and community investment. As we look to the year ahead and beyond, 
I want to assure you that the Board, management team and employees of Provident remain dedicated to carrying forward the Company’s reputation and legacy, just as we have since our founding. We will remain true to our community banking roots and focus on serving the families and small businesses of the Inland Empire. That heritage is central to who we are, and we intend to build on it in the years to come.
In closing, I would likewant to recognize and thank our employees and Directors for their commitment and service to Provident. Their efforts make our success possible. I also extend my sincere appreciation to our customers, shareholders, and the communities we serve for the confidence you place in us. Our continued success depends on the trust you place in Provident, and we are grateful for the opportunity to serve you.
Sincerely,
/s/ Craig G. Blunden
Craig G. Blunden
Chairman of the Board of Directors
03 · YÊU CẦU 2
"Bây giờ hãy rút gọn xuống còn khoảng 600 từ cho bản web"
Nội dung nhân viên truyền thông đã nhập
Thanks. Please accept all of your tracked changes, then turn the letter into the web version in the same file, again with tracked changes so Craig can see what was cut:
1. Switch percentages to numerals with % (61%, 32%, 1%, 2%, 3%, 3.09%).
2. Cut the letter from about 1,100 words to about 600. Trim the interest-rate and real-estate commentary in the opening paragraphs first.
3. Keep the 'A Final Word' section in full.
4. Any figure that stays must keep its value. Financial Highlights stays untouched.
Những gì đã làm
- Tiếp tục làm việc trên tệp Word đã được giao cho yêu cầu 1.
- Cắt bức thư từ 1.082 từ xuống 600 từ. Phần lớn nội dung bị cắt đến từ phần mở đầu về lãi suất, thị trường trái phiếu và bất động sản California theo yêu cầu: ba đoạn đó đã giảm từ 429 từ xuống còn 63 từ.
- Cũng đã lược bớt các câu về sự cạnh tranh tiền gửi dưới mục "Fiscal 2026" và câu cuối cùng dưới mục "Fiscal 2027".
- Đã viết mọi tỷ lệ phần trăm thành chữ số kèm theo %: 61%, 32%, 1%, 2%, 3% và 3.09%, giữ nguyên các giá trị như trước.
- Giữ nguyên vẹn từng chữ phần "A Final Word" và không chạm đến các bảng Financial Highlights.
Các chỉnh sửa tiếp tục được thực hiện trực tiếp vào tệp. Phần đánh dấu đỏ là báo cáo theo dõi thay đổi trên các tệp yêu cầu 1 và yêu cầu 2, với số lượng từ của từng đoạn được ghi ở lề.
Message From the Chairman
Dear Fellow Shareholders:
I am pleased to forward our Annual Report for fiscal 2026 highlighting our financial results. Last year I noted in the Chairman’s Message that “… the market is expecting the easing of monetary policy to resume later this calendar year but we are cognizant of the weaker employment data that was recently released and its potential downstream impact on the economy. We are also observing some weaknesses in the California real estate market.” A year later, after three successive quarter-point reductions in the federal funds rate in the latter part of 2025, the Federal Open Market Committee, or FOMC, has held rates steady. At present, the market does not appear to expect additional interest rate cuts for the remainder of this year and possibly into 2027. Indeed, some market observers believe a rate hike is possible later this year. We have also seen an important shift in the bond market. The U.S. Treasury yield curve emerged from its extended inversion and returned to a more normal upward slope. As short-term rates have been anchored by the federal funds rate, longer-term bond yields have been steadily rising, further steepening the yield curve. This movement reflects continued uncertainty regarding inflation, the state of the federal budget deficit and the potential for geopolitical developments to create supply-chain or energy-related pressures.
For banks, a steeper yield curve can be beneficial. A bank’s net interest margin benefits from the widening spread between the cost of deposits and other short-term funding and yields earned on loans. New loans are being originated at higher rates, and adjustable-rate loans are repricing upward. At the same time, higher long-term rates weigh on the real estate market, especially in high-cost markets such as California. Mortgage payments have become increasingly unaffordable for prospective buyers, while many existing homeowners remain locked into mortgages with rates well below current levels. At the current level of mortgage rates, residential purchase and refinancing activities have been curtailed. Even so, California real estate values have been resilient. Prices have generally held up well across the markets we serve, reflecting the underlying strength in the economy and limited housing supply in our local communities.
In this evolving market, one thing remains constant: we are well positioned, supported by a strong capital position and pristine credit quality. Our long-standing credit culture has served us well and positioned the Company among the top performers across key credit quality metrics. Our goal is to remain good stewards of our capital by executing a strategy of disciplined, sustainable growth, conservative credit underwriting, and consistent returns of capital to our shareholders.
Fiscal 2026
Last year, I said our fiscal 2026 Business Plan reflected measured growth in loans and retail deposits, disciplined control of operating expenses, and sound capital management. Our financial results, described in the following Financial Highlights, reflected improved earnings compared to the prior year, despite a moderate decline in total assets.
50During fiscal 2026, as the yield curve normalized, we adjusted our strategy to support increased loan production. Following a 61 percent% increase in loan production during fiscal 2025, we achieved an additional 32 percent% increase in fiscal 2026. However, these production gains were fully offset by higher-than-normal levels of loan prepayments. As a result, our loans held for investment decreased by approximately one percent for the fiscal year. The deposit landscape remained challenging, as competition for deposits continued to be intense. Competitors of all sizes, including large national banks, aggressively marketed promotional deposit rates that remain elevated today, even as the FOMC lowered short-term rates in 2025. We made accommodations, as appropriate, to our pricing based on our evaluation of the customer relationships, while maintaining our pricing discipline, and augmented our funding needs with certificates of deposit and borrowings. Total deposits increased two percent during the fiscal year although transaction accounts declined three percent. Our net interest margin exceeded three percent for the year, reaching 3.09 percent1% for the fiscal year. Total deposits increased 2% during the fiscal year although transaction accounts declined 3%. Our net interest margin exceeded 3% for the year, reaching 3.09%, driven primarily by the repricing of Federal Home Loan Bank advances to lower rates as they matured. Despite inflationary pressures, operating expenses increased by less than one percent1% for the fiscal year. Finally, we recorded no loan charge-offs during fiscal 2026 — our eighth consecutive year without reporting a net charge-off.
Returning capital to our shareholders is a priority. During fiscal 2026, we maintained our quarterly cash dividend of $0.14 per share and increased our share repurchases to approximately 344,000 shares, compared to approximately 285,000 shares in fiscal 2025.
38Fiscal 2027
As we look to fiscal 2027, our priorities remain consistent: measured growth in loans and retail deposits; disciplined expense management; and sound capital management. We believe this approach is the right course in an economy that continues to expand, while recognizing the need to remain cautious amid ongoing market and geopolitical uncertainties. We expect to continue returning capital to shareholders through dividends and share repurchases while maintaining sufficient capital to support our business strategy and withstand potential losses under adverse conditions. We remain committed to single-family residential, multi-family, and commercial real estate mortgage lending as our primary sources of asset growth and our retail branch network will continue to serve as the primary source of the Bank’s funding.
A Final Word
This year, Provident proudly celebrates the 70th anniversary of its founding, serving the great city of Riverside and its surrounding communities. As the largest independent community bank headquartered in Riverside County, we are proud of our distinguished history as a trusted provider of banking services. Just as importantly, we are proud of the commitment demonstrated throughout our organization to strengthen the communities we serve through volunteer service, charitable support and community investment. As we look to the year ahead and beyond, I want to assure you that the Board, management team and employees of Provident remain dedicated to carrying forward the Company’s reputation and legacy, just as we have since our founding. We will remain true to our community banking roots and focus on serving the families and small businesses of the Inland Empire. That heritage is central to who we are, and we intend to build on it in the years to come.
154In closing, I want to recognize and thank our employees and Directors for their commitment and service to Provident. Their efforts make our success possible. I also extend my sincere appreciation to our customers, shareholders, and the communities we serve for the confidence you place in us. Our continued success depends on the trust you place in Provident, and we are grateful for the opportunity to serve you.
68Sincerely,
/s/ Craig G. Blunden
Craig G. Blunden
Chairman of the Board of Directors
Financial Highlights
The following tables set forth information concerning the consolidated financial position and results of operations of the Corporation and its subsidiary at the dates and for the periods indicated.
| (In Thousands, Except Per Share Information) | 2026 | 2025 | 2024 | 2023 | 2022 |
|---|---|---|---|---|---|
| FINANCIAL CONDITION DATA: | |||||
| Total assets | $1,208,161 | $1,245,613 | $1,272,200 | $1,332,948 | $1,187,038 |
| Loans held for investment, net | 1,032,682 | 1,045,745 | 1,052,979 | 1,077,629 | 939,992 |
| Cash and cash equivalents | 49,210 | 53,090 | 51,376 | 65,849 | 23,414 |
| Investment securities | 90,523 | 111,006 | 131,900 | 156,492 | 188,421 |
| Deposits | 910,383 | 888,772 | 888,348 | 950,571 | 955,504 |
| Borrowings | 157,046 | 213,073 | 238,500 | 235,009 | 85,000 |
| Stockholders’ equity | 126,220 | 128,545 | 129,941 | 129,687 | 128,650 |
| Book value per share | 20.15 | 19.54 | 18.98 | 18.41 | 17.66 |
| OPERATING DATA: | |||||
| Interest income | $55,889 | $56,624 | $54,730 | $45,992 | $34,730 |
| Interest expense | 19,561 | 21,155 | 19,807 | 9,007 | 3,135 |
| Net interest income | 36,328 | 35,469 | 34,923 | 36,985 | 31,595 |
| (Recovery of) provision for credit losses | (553) | (666) | (63) | 374 | (2,462) |
| Net interest income after (recovery of) provision for credit losses | 36,881 | 36,135 | 34,986 | 36,611 | 34,057 |
| Loan servicing and other fees | 583 | 419 | 337 | 414 | 1,056 |
| Deposit account fees | 1,067 | 1,112 | 1,154 | 1,296 | 1,302 |
| Card and processing fees | 1,203 | 1,265 | 1,384 | 1,525 | 1,639 |
| Other non-interest income | 873 | 735 | 1,066 | 840 | 719 |
| Operating expenses | 30,971 | 30,793 | 28,540 | 28,270 | 25,915 |
| Income before income taxes | 9,636 | 8,873 | 10,387 | 12,416 | 12,858 |
| Provision for income taxes | 2,981 | 2,618 | 3,036 | 3,824 | 3,765 |
| Net income | $6,655 | $6,255 | $7,351 | $8,592 | $9,093 |
| Basic earnings per share | $1.04 | $0.93 | $1.06 | $1.20 | $1.23 |
| Diluted earnings per share | $1.03 | $0.93 | $1.06 | $1.19 | $1.22 |
| Cash dividend per share | $0.56 | $0.56 | $0.56 | $0.56 | $0.56 |
Chỉnh sửa trực tiếp bên trong báo cáo thường niên, không phải dán lại văn bản viết lại
Hầu hết các công cụ AI trả lại bức thư dưới dạng văn bản trò chuyện và ai đó phải dán nó vào lại báo cáo. hoạt động trực tiếp trong tệp Word, để nguyên các con số và bảng biểu, và báo cáo theo dõi thay đổi của nó cho người xem thấy mọi chỉnh sửa.
ĐỌC TIẾP
Đọc ví dụ thực tế khác
Marketing và truyền thông
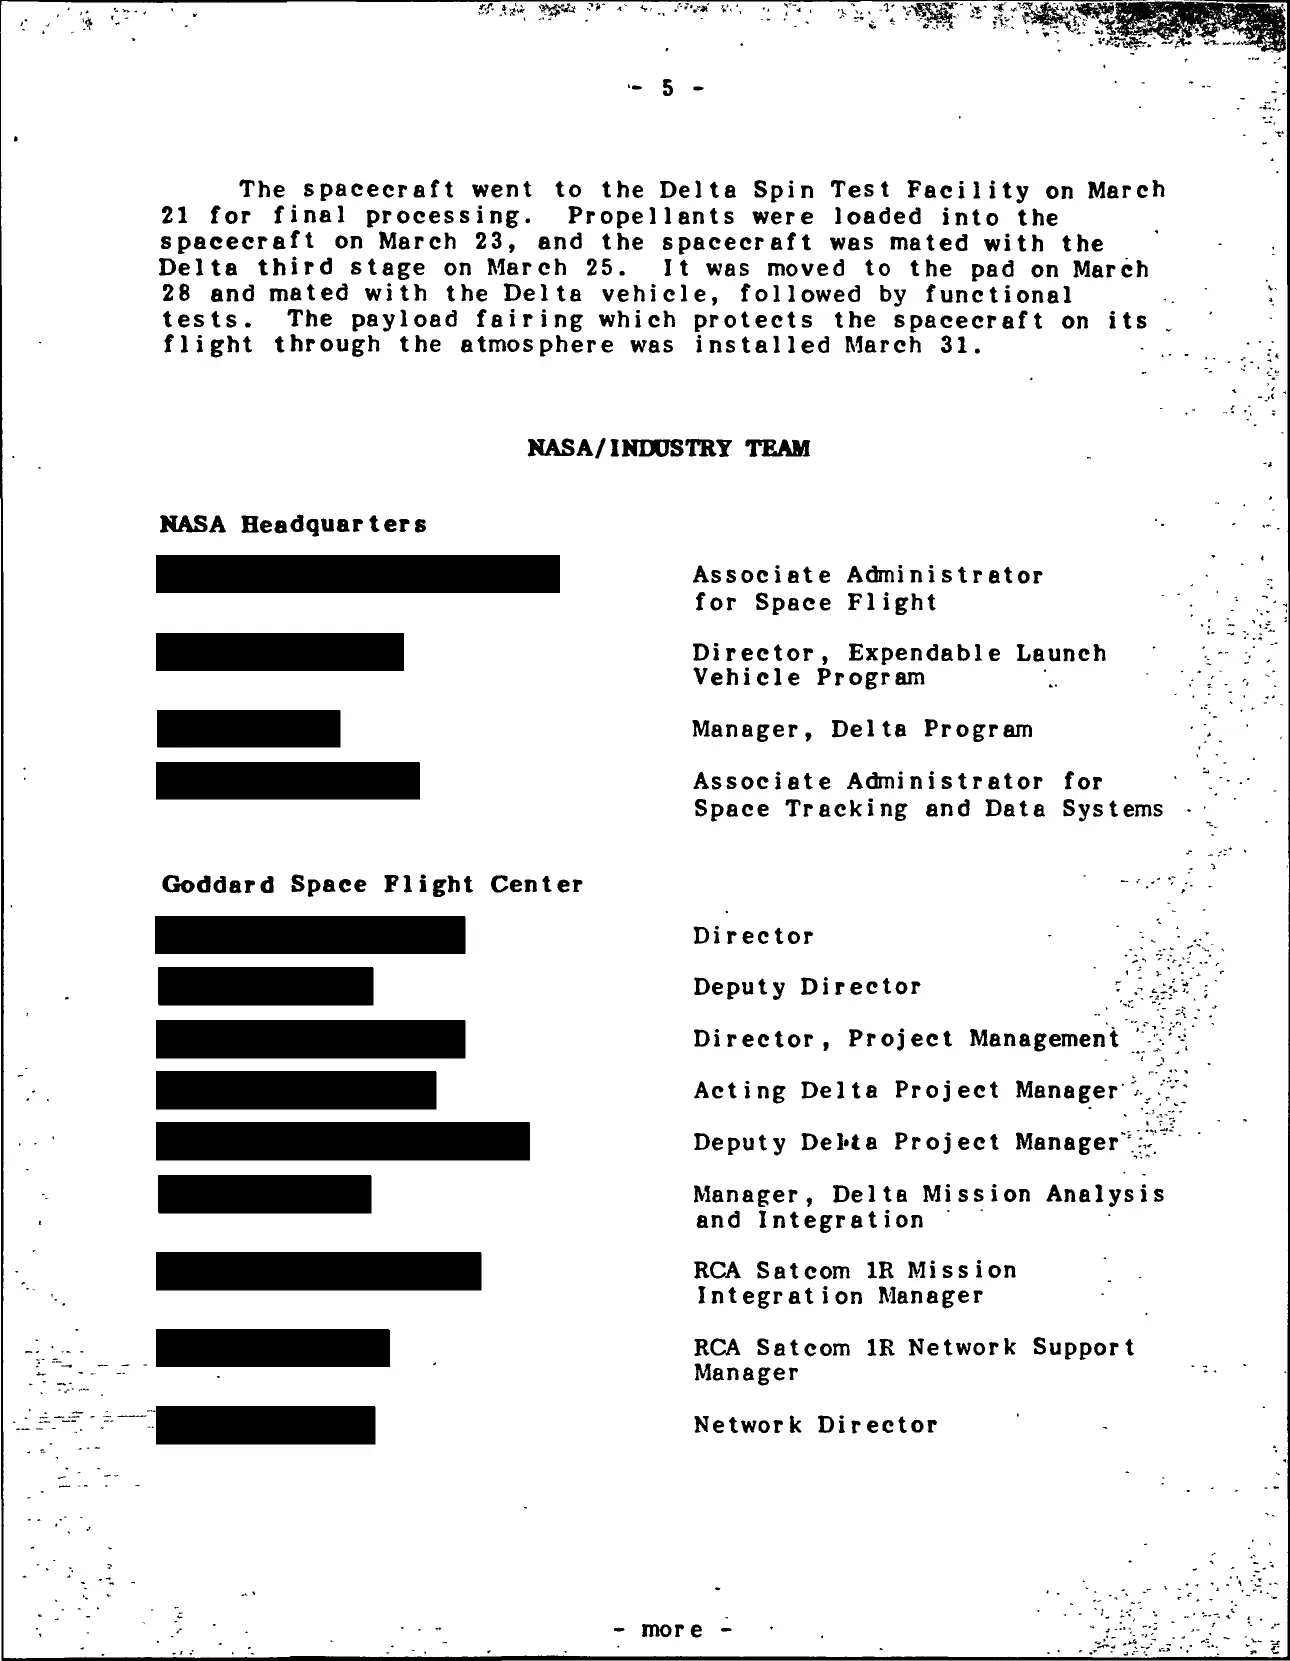
Bộ tài liệu báo chí NASA 1983 đã quét được biên tập, sau đó được khôi phục một phần
Y tế
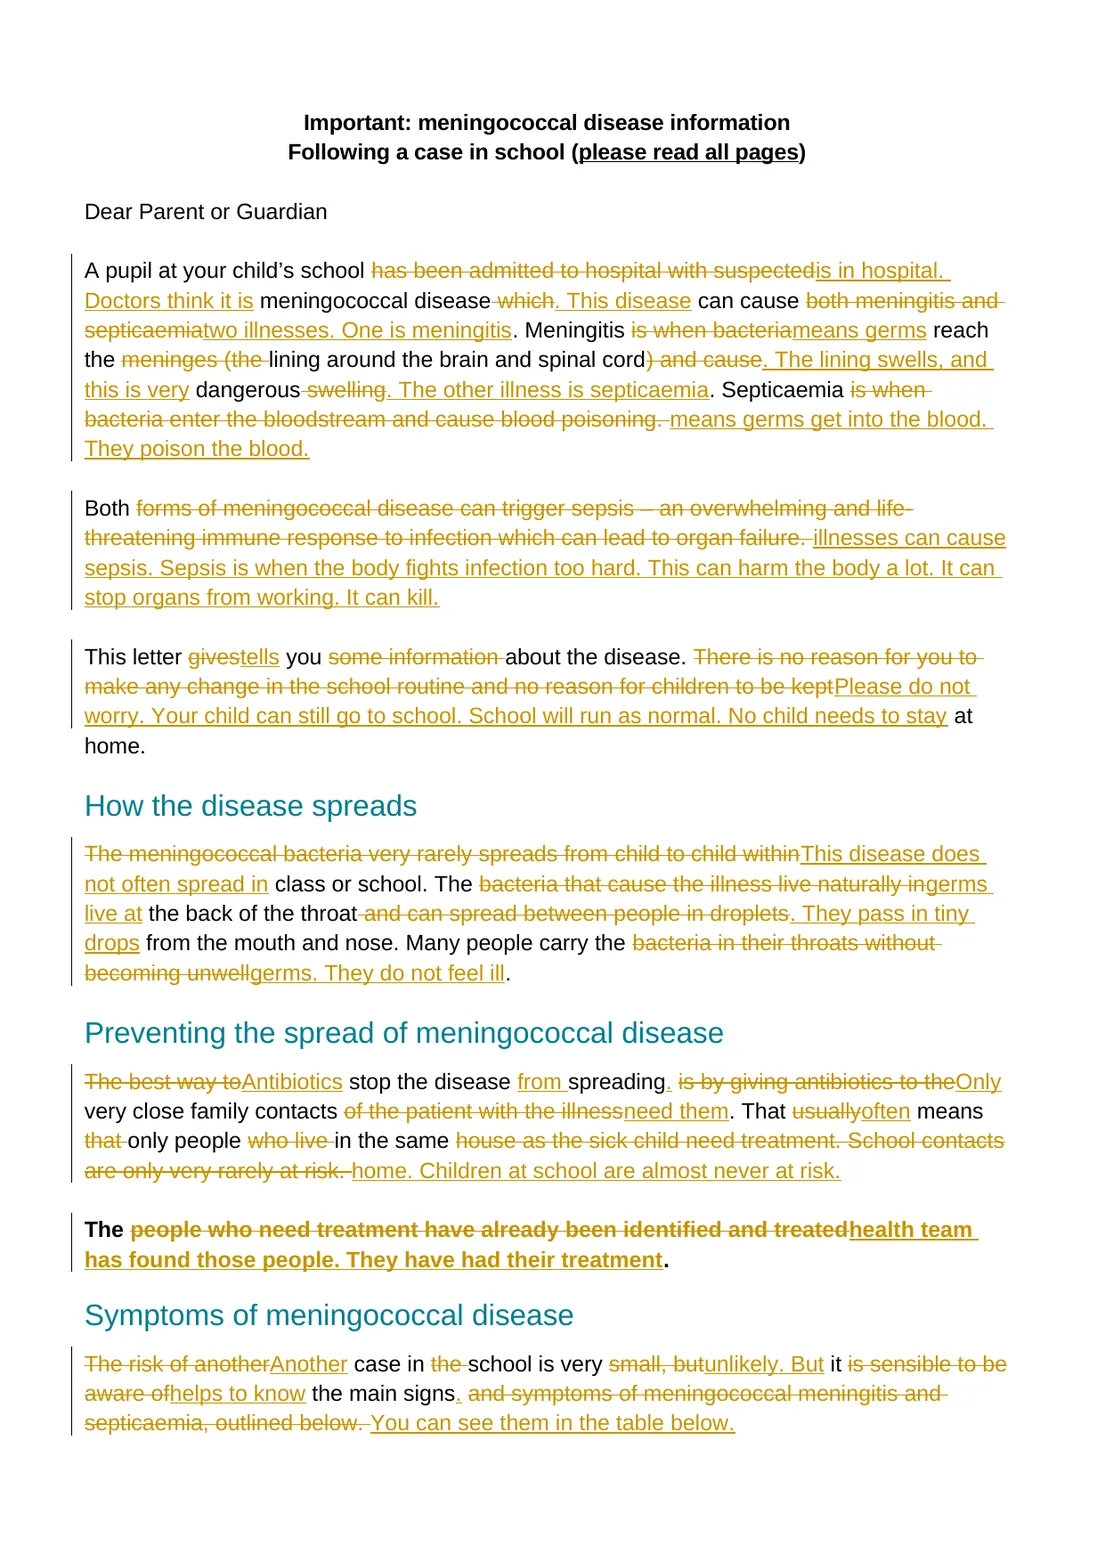
Thư y tế gửi phụ huynh được đơn giản hóa dưới dạng thay đổi được theo dõi, sau đó là bản tiếng Ba Lan
Nhân viên ngân hàng và chuyên gia tư vấn
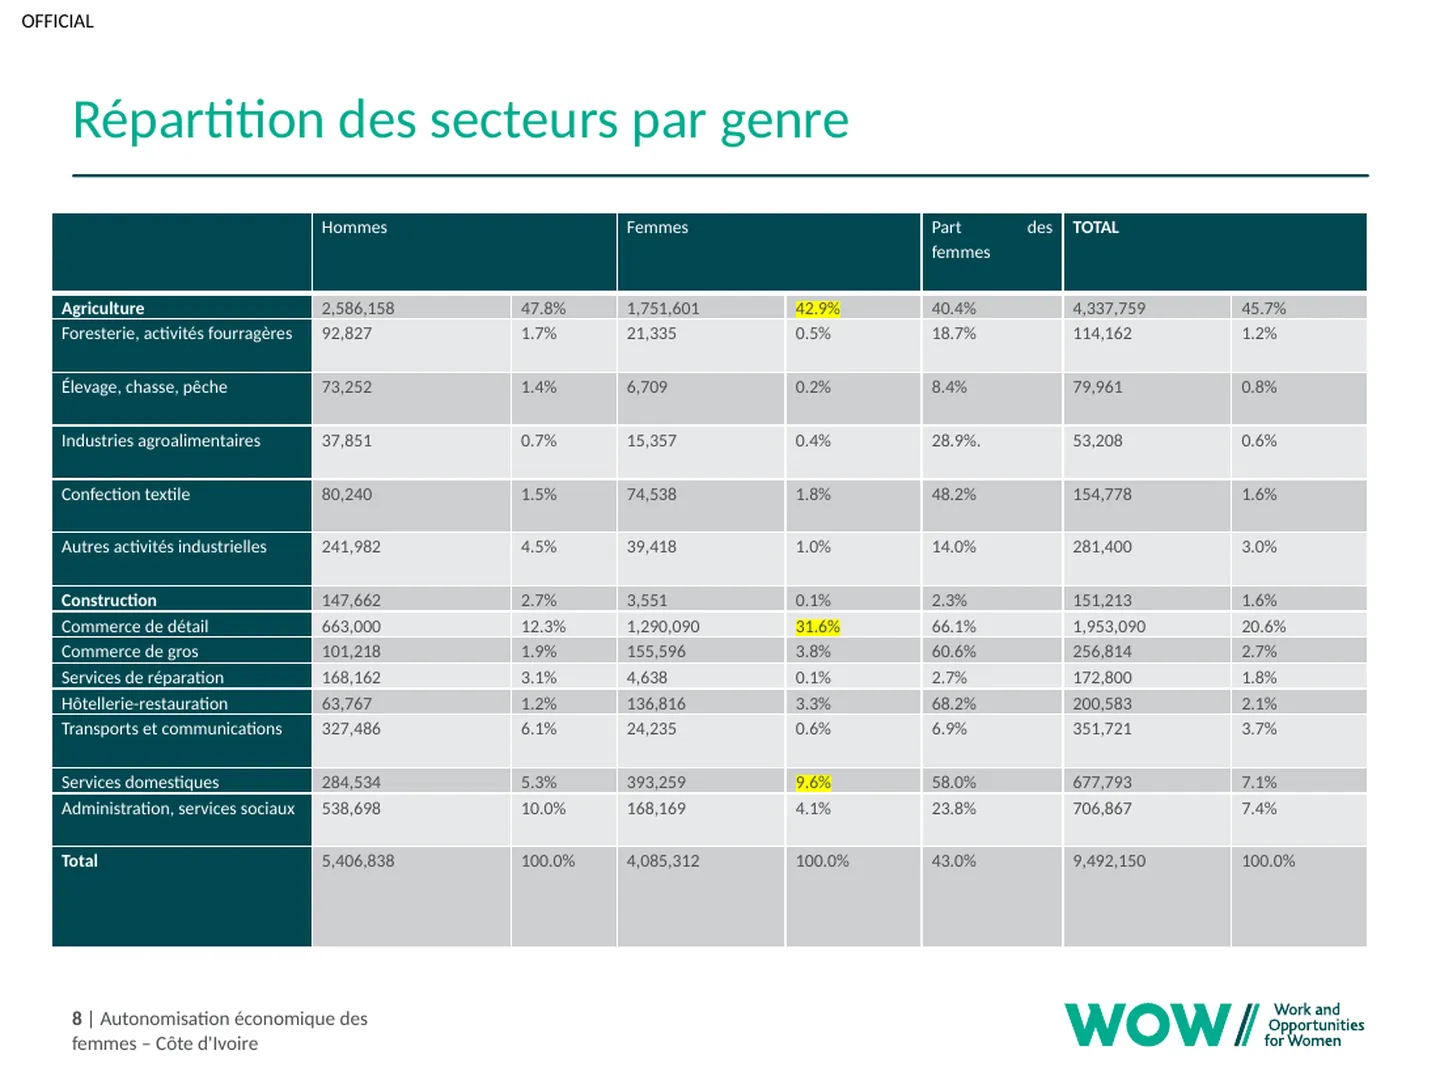
Bộ 23 slide về phát triển sang tiếng Pháp, rồi sửa ba điểm
Xem tất cả 19 ví dụ thực tế →Tất cả ví dụ dành cho Marketing và truyền thông →