ตัวอย่างการใช้งาน · การพิสูจน์อักษรใน WORD
พิสูจน์อักษรจดหมายของประธานกรรมการ แล้วตัดทอนเหลือเป็นเวอร์ชันเว็บ 600 คำ
เจ้าหน้าที่ฝ่ายสื่อสารองค์กรของธนาคารชุมชนได้รับรายงานประจำปีในรูปแบบไฟล์ Word พวกเขาขอให้ ช่วยพิสูจน์อักษรจดหมายจากประธานกรรมการตามสไตล์ AP แบบเบาๆ โดยไม่แตะต้องตัวเลข ข้อความอ้างอิงจากจดหมายปีที่แล้ว หรือตารางการเงิน
แก้ไขส่วนขยายที่ลอยเคว้ง ปรับสำนวนให้อ่านราบรื่น และรวมสามประโยคที่ถูกแบ่งแยกจากการแปลงไฟล์กลับเป็นประโยคเดียว ทั้งหมดทำในไฟล์เดิม และคงตัวเลขทุกตัวไว้ตามเดิม จากนั้นตัดทอนจดหมายจาก 1,093 คำเหลือ 600 คำสำหรับเว็บ โดยเขียนตัวเลขเปอร์เซ็นต์เป็นตัวเลข และคงส่วนท้ายไว้ครบถ้วน
1การอัปโหลด: รายงานประจำปีของธนาคาร ในรูปแบบไฟล์ Word
Message From the Chairman
Dear Fellow Shareholders:
Fiscal 2026
Fiscal 2027
A Final Word
Sincerely,
Financial Highlights
- 1,093 → 600จำนวนคำในจดหมายหลังคำขอที่ 2
- 3ประโยคที่ถูกแยกถูกรวมเข้าด้วยกันอีกครั้ง
- 8ตัวเลข "ร้อยละ" เปลี่ยนเป็น % คงค่าเดิมไว้
- 0การแก้ไขนอกเหนือจากตัวจดหมาย
เปิดไฟล์ต้นฉบับจริง
นี่คือไฟล์จริงจากการทำงานจริง ดาวน์โหลดและเปิดดูได้ใน Word
ที่มาของไฟล์: Provident Financial Holdings, Inc., รายงานประจำปี 2026 สำหรับผู้ถือหุ้น ยื่นต่อ SEC เป็นเอกสารแนบ 13 ในแบบ Form 10-K เป็นการยื่นเอกสารต่อสาธารณะ เนื้อหาเป็นของบริษัท
01 · ไฟล์เริ่มต้น
รายงานประจำปี 9 หน้า จดหมายอยู่ในหน้าที่ 2
รายงานประจำปีสำหรับผู้ถือหุ้นของธนาคารขนาดเล็กที่จดทะเบียนในตลาดหลักทรัพย์ ประกอบด้วย: ปก, จดหมายจากประธานกรรมการ, ตารางสรุปข้อมูลทางการเงิน, ข้อมูลผู้ถือหุ้น, รายชื่อคณะกรรมการ และรายชื่อสาขา รวมเก้าหน้าและหกตารางในไฟล์ Word เดียว
เราสร้างไฟล์ Word นี้จากหน้าเว็บเอกสารยื่นต่อ SEC ที่เป็นสาธารณะ โดยใช้ LibreOffice กระบวนการแปลงไฟล์ทำให้ประโยคสามประโยคถูกตัดแยกออกเป็นสองย่อหน้า ซึ่งเป็นข้อผิดพลาดทั่วไปเมื่อหน้าเว็บกลายมาเป็นไฟล์ Word โดยในคำสั่งระบุตำแหน่งทั้งสามจุดนี้ไว้
02 · คำขอที่ 1
"พิสูจน์อักษรจดหมายตามสไตล์ AP และแก้ไขเพียงเล็กน้อย"
สิ่งที่เจ้าหน้าที่ฝ่ายสื่อสารองค์กรพิมพ์
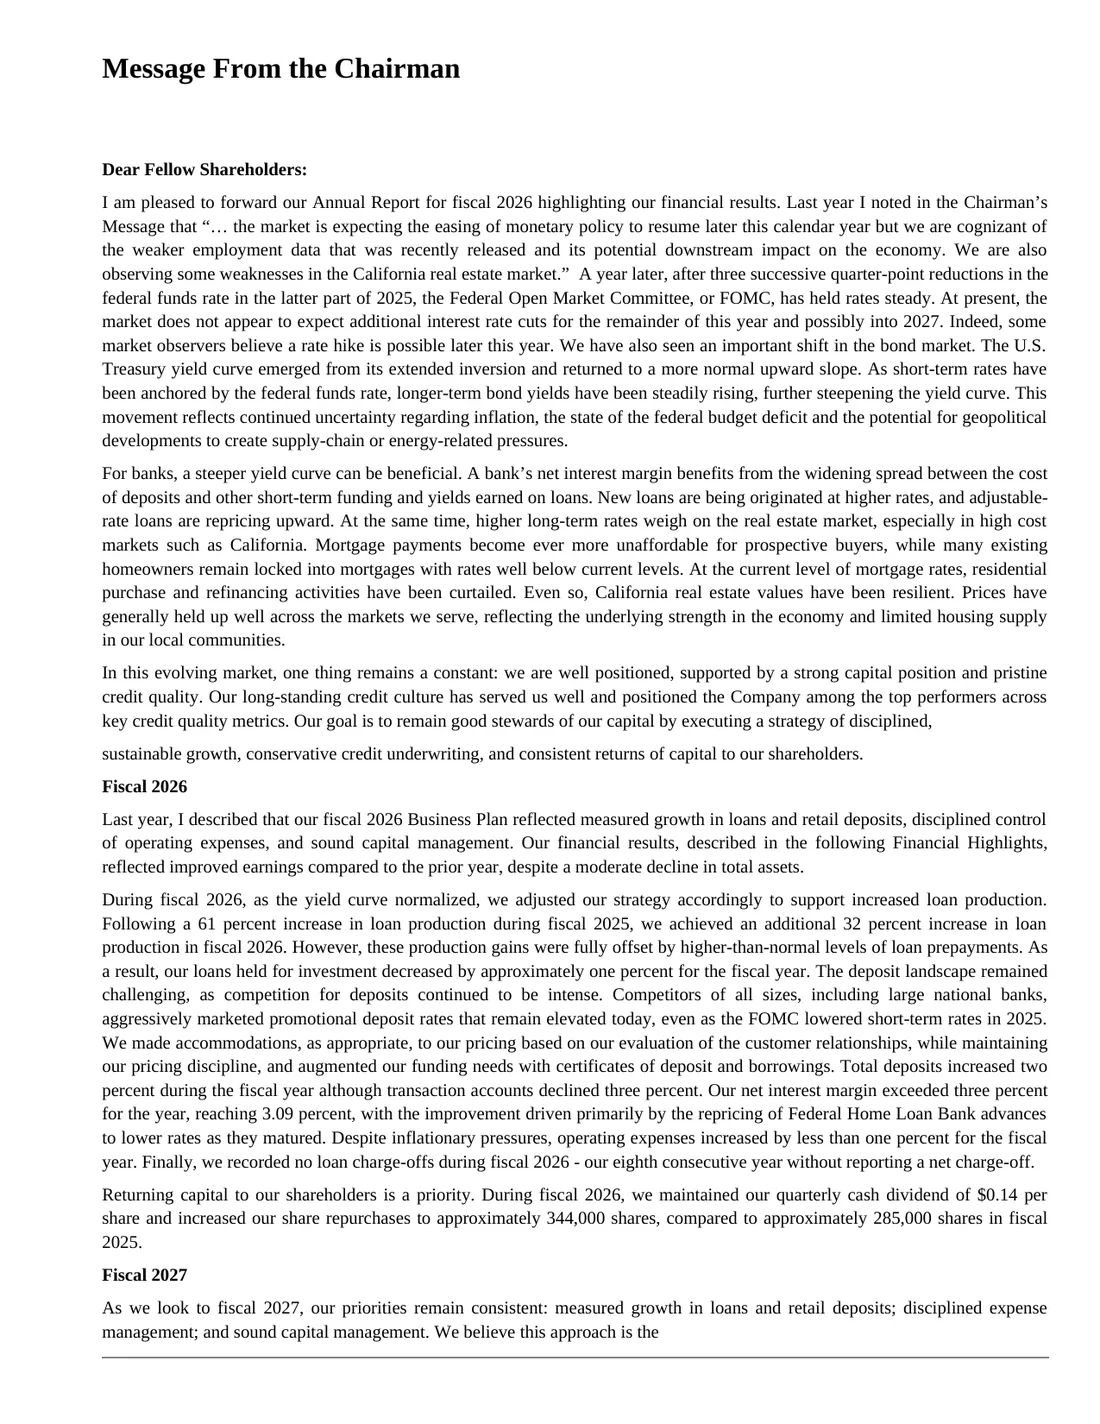
Please proofread the 'Message From the Chairman' (from 'Dear Fellow Shareholders:' down to Craig Blunden's signature block) with tracked changes, AP style.

- Fix grammar, punctuation and awkward phrasing, but keep the edits light.
- Don't change any figures or the meaning. Leave the way numbers are written ('61 percent', 'one percent') alone for now.
- The quotation from last year's letter in the first paragraph ('… the market is expecting … California real estate market.') must stay word for word.
- Three sentences were split into two paragraphs when the file was converted: after 'disciplined,', after 'this approach is the', and after 'the year ahead and beyond,'. Join each back into one paragraph.
- Don't touch the Financial Highlights tables or anything after the letter.
สิ่งที่ ทำ
- แก้ไขจดหมายภายในไฟล์ Word ที่อัปโหลด เนื้อหาในหน้าอื่นๆ ทั้งหมดคงเดิม
- แก้ไขส่วนขยายที่ลอยเคว้ง (dangling modifier): จากเดิม "As the largest independent community bank headquartered in Riverside County, I am proud" เปลี่ยนเป็น "we are proud" ทั้งในประโยคนี้และประโยคถัดไป
- แก้ไขตามสไตล์ AP เล็กน้อย: ใส่ยัติภังค์ใน "high-cost markets" ใส่เครื่องหมาย em dash แบบเว้นวรรคใน "fiscal 2026 — our eighth consecutive year" และเปลี่ยน "remains a constant" เป็น "remains constant"
- ปรับสำนวนที่ดูแปลกให้อ่านราบรื่นขึ้น เช่น เปลี่ยน "Last year, I described that" เป็น "Last year, I said" และตัดคำที่ไม่จำเป็นออกบางคำ
- รวมสามประโยคที่ถูกแยกออกจากกันกลับเป็นย่อหน้าเดียวต่อประโยค
- คงข้อความอ้างอิงจากจดหมายปีที่แล้ว ทุกตัวเลข และรูปแบบการเขียนตัวเลขทั้งหมดไว้ตามเดิมทุกประการ
คำสั่งขอให้มีการติดตามการเปลี่ยนแปลง แต่ เขียนการแก้ไขลงในไฟล์โดยตรง ดังนั้นรอยแก้ด้านล่างจึงมาจากฟังก์ชัน "สร้างรายงานการติดตามการเปลี่ยนแปลง" ของ เอง โดยรันเทียบไฟล์ก่อนและหลังการแก้ไข
Message From the Chairman
Dear Fellow Shareholders:
I am pleased to forward our Annual Report for fiscal 2026 highlighting our financial results. Last year I noted in the Chairman’s Message that “… the market is expecting the easing of monetary policy to resume later this calendar year but we are cognizant of the weaker employment data that was recently released and its potential downstream impact on the economy. We are also observing some weaknesses in the California real estate market.” A year later, after three successive quarter-point reductions in the federal funds rate in the latter part of 2025, the Federal Open Market Committee, or FOMC, has held rates steady. At present, the market does not appear to expect additional interest rate cuts for the remainder of this year and possibly into 2027. Indeed, some market observers believe a rate hike is possible later this year. We have also seen an important shift in the bond market. The U.S. Treasury yield curve emerged from its extended inversion and returned to a more normal upward slope. As short-term rates have been anchored by the federal funds rate, longer-term bond yields have been steadily rising, further steepening the yield curve. This movement reflects continued uncertainty regarding inflation, the state of the federal budget deficit and the potential for geopolitical developments to create supply-chain or energy-related pressures.
For banks, a steeper yield curve can be beneficial. A bank’s net interest margin benefits from the widening spread between the cost of deposits and other short-term funding and yields earned on loans. New loans are being originated at higher rates, and adjustable-rate loans are repricing upward. At the same time, higher long-term rates weigh on the real estate market, especially in high -cost markets such as California. Mortgage payments have become ever moreincreasingly unaffordable for prospective buyers, while many existing homeowners remain locked into mortgages with rates well below current levels. At the current level of mortgage rates, residential purchase and refinancing activities have been curtailed. Even so, California real estate values have been resilient. Prices have generally held up well across the markets we serve, reflecting the underlying strength in the economy and limited housing supply in our local communities.
In this evolving market, one thing remains a constant: we are well positioned, supported by a strong capital position and pristine credit quality. Our long-standing credit culture has served us well and positioned the Company among the top performers across key credit quality metrics. Our goal is to remain good stewards of our capital by executing a strategy of disciplined, 
sustainable growth, conservative credit underwriting, and consistent returns of capital to our shareholders.
Fiscal 2026
Last year, I described thatsaid our fiscal 2026 Business Plan reflected measured growth in loans and retail deposits, disciplined control of operating expenses, and sound capital management. Our financial results, described in the following Financial Highlights, reflected improved earnings compared to the prior year, despite a moderate decline in total assets.
During fiscal 2026, as the yield curve normalized, we adjusted our strategy accordingly to support increased loan production. Following a 61 percent increase in loan production during fiscal 2025, we achieved an additional 32 percent increase in loan production in fiscal 2026. However, these production gains were fully offset by higher-than-normal levels of loan prepayments. As a result, our loans held for investment decreased by approximately one percent for the fiscal year. The deposit landscape remained challenging, as competition for deposits continued to be intense. Competitors of all sizes, including large national banks, aggressively marketed promotional deposit rates that remain elevated today, even as the FOMC lowered short-term rates in 2025. We made accommodations, as appropriate, to our pricing based on our evaluation of the customer relationships, while maintaining our pricing discipline, and augmented our funding needs with certificates of deposit and borrowings. Total deposits increased two percent during the fiscal year although transaction accounts declined three percent. Our net interest margin exceeded three percent for the year, reaching 3.09 percent, with the improvement driven primarily by the repricing of Federal Home Loan Bank advances to lower rates as they matured. Despite inflationary pressures, operating expenses increased by less than one percent for the fiscal year. Finally, we recorded no loan charge-offs during fiscal 2026 -— our eighth consecutive year without reporting a net charge-off.
Returning capital to our shareholders is a priority. During fiscal 2026, we maintained our quarterly cash dividend of $0.14 per share and increased our share repurchases to approximately 344,000 shares, compared to approximately 285,000 shares in fiscal 2025.
Fiscal 2027
As we look to fiscal 2027, our priorities remain consistent: measured growth in loans and retail deposits; disciplined expense management; and sound capital management. We believe this approach is the 
right course in an economy that continues to expand, while recognizing the need to remain cautious amid ongoing market and geopolitical uncertainties. We expect to continue returning capital to shareholders through dividends and share repurchases while maintaining sufficient capital to support our business strategy and withstand potential losses under adverse conditions. We remain committed to single-family residential, multi-family, and commercial real estate mortgage lending as our primary sources of asset growth and our retail branch network will continue to serve as the primary source of the Bank’s funding.
A Final Word
This year, Provident proudly celebrates the 70th anniversary of its founding, serving the great city of Riverside and its surrounding communities. As the largest independent community bank headquartered in Riverside County, I amwe are proud of our distinguished history as a trusted provider of banking services. Just as importantly, I amwe are proud of the commitment demonstrated throughout our organization to strengthen the communities we serve through volunteer service, charitable support and community investment. As we look to the year ahead and beyond, 
I want to assure you that the Board, management team and employees of Provident remain dedicated to carrying forward the Company’s reputation and legacy, just as we have since our founding. We will remain true to our community banking roots and focus on serving the families and small businesses of the Inland Empire. That heritage is central to who we are, and we intend to build on it in the years to come.
In closing, I would likewant to recognize and thank our employees and Directors for their commitment and service to Provident. Their efforts make our success possible. I also extend my sincere appreciation to our customers, shareholders, and the communities we serve for the confidence you place in us. Our continued success depends on the trust you place in Provident, and we are grateful for the opportunity to serve you.
Sincerely,
/s/ Craig G. Blunden
Craig G. Blunden
Chairman of the Board of Directors
03 · คำขอที่ 2
"ตอนนี้ตัดให้เหลือประมาณ 600 คำสำหรับเว็บ"
สิ่งที่เจ้าหน้าที่ฝ่ายสื่อสารองค์กรพิมพ์
Thanks. Please accept all of your tracked changes, then turn the letter into the web version in the same file, again with tracked changes so Craig can see what was cut:
1. Switch percentages to numerals with % (61%, 32%, 1%, 2%, 3%, 3.09%).
2. Cut the letter from about 1,100 words to about 600. Trim the interest-rate and real-estate commentary in the opening paragraphs first.
3. Keep the 'A Final Word' section in full.
4. Any figure that stays must keep its value. Financial Highlights stays untouched.
สิ่งที่ ทำ
- ทำงานต่อในไฟล์ Word ที่ส่งมอบไปแล้วสำหรับคำขอที่ 1
- ตัดเนื้อหาจดหมายจาก 1,082 คำเหลือ 600 คำ ส่วนใหญ่ตัดออก 3 ย่อหน้าแรกเกี่ยวกับอัตราดอกเบี้ย ตลาดพันธบัตร และอสังหาริมทรัพย์ในแคลิฟอร์เนียตามที่ขอ: จากเดิม 429 คำเหลือ 63 คำ
- รวมถึงตัดทอนประโยคเกี่ยวกับการแข่งขันด้านเงินฝากภายใต้หัวข้อ "Fiscal 2026" และประโยคสุดท้ายภายใต้หัวข้อ "Fiscal 2027"
- เขียนตัวเลขเปอร์เซ็นต์ทุกตัวให้อยู่ในรูปตัวเลขพร้อมเครื่องหมาย %: 61%, 32%, 1%, 2%, 3% และ 3.09% โดยใช้ค่าเดิมทั้งหมด
- คงข้อความ "A Final Word" ไว้ตามเดิมทุกคำ และปล่อยตารางสรุปข้อมูลทางการเงินไว้โดยไม่แก้ไข
การแก้ไขถูกใส่ลงไปในไฟล์โดยตรงเช่นเคย รอยแก้ (redline) ด้านล่างคือรายงานการติดตามการเปลี่ยนแปลง (track-changes report) ของไฟล์คำขอที่ 1 และคำขอที่ 2 พร้อมจำนวนคำของแต่ละย่อหน้าตรงขอบกระดาษ
Message From the Chairman
Dear Fellow Shareholders:
I am pleased to forward our Annual Report for fiscal 2026 highlighting our financial results. Last year I noted in the Chairman’s Message that “… the market is expecting the easing of monetary policy to resume later this calendar year but we are cognizant of the weaker employment data that was recently released and its potential downstream impact on the economy. We are also observing some weaknesses in the California real estate market.” A year later, after three successive quarter-point reductions in the federal funds rate in the latter part of 2025, the Federal Open Market Committee, or FOMC, has held rates steady. At present, the market does not appear to expect additional interest rate cuts for the remainder of this year and possibly into 2027. Indeed, some market observers believe a rate hike is possible later this year. We have also seen an important shift in the bond market. The U.S. Treasury yield curve emerged from its extended inversion and returned to a more normal upward slope. As short-term rates have been anchored by the federal funds rate, longer-term bond yields have been steadily rising, further steepening the yield curve. This movement reflects continued uncertainty regarding inflation, the state of the federal budget deficit and the potential for geopolitical developments to create supply-chain or energy-related pressures.
For banks, a steeper yield curve can be beneficial. A bank’s net interest margin benefits from the widening spread between the cost of deposits and other short-term funding and yields earned on loans. New loans are being originated at higher rates, and adjustable-rate loans are repricing upward. At the same time, higher long-term rates weigh on the real estate market, especially in high-cost markets such as California. Mortgage payments have become increasingly unaffordable for prospective buyers, while many existing homeowners remain locked into mortgages with rates well below current levels. At the current level of mortgage rates, residential purchase and refinancing activities have been curtailed. Even so, California real estate values have been resilient. Prices have generally held up well across the markets we serve, reflecting the underlying strength in the economy and limited housing supply in our local communities.
In this evolving market, one thing remains constant: we are well positioned, supported by a strong capital position and pristine credit quality. Our long-standing credit culture has served us well and positioned the Company among the top performers across key credit quality metrics. Our goal is to remain good stewards of our capital by executing a strategy of disciplined, sustainable growth, conservative credit underwriting, and consistent returns of capital to our shareholders.
Fiscal 2026
Last year, I said our fiscal 2026 Business Plan reflected measured growth in loans and retail deposits, disciplined control of operating expenses, and sound capital management. Our financial results, described in the following Financial Highlights, reflected improved earnings compared to the prior year, despite a moderate decline in total assets.
50During fiscal 2026, as the yield curve normalized, we adjusted our strategy to support increased loan production. Following a 61 percent% increase in loan production during fiscal 2025, we achieved an additional 32 percent% increase in fiscal 2026. However, these production gains were fully offset by higher-than-normal levels of loan prepayments. As a result, our loans held for investment decreased by approximately one percent for the fiscal year. The deposit landscape remained challenging, as competition for deposits continued to be intense. Competitors of all sizes, including large national banks, aggressively marketed promotional deposit rates that remain elevated today, even as the FOMC lowered short-term rates in 2025. We made accommodations, as appropriate, to our pricing based on our evaluation of the customer relationships, while maintaining our pricing discipline, and augmented our funding needs with certificates of deposit and borrowings. Total deposits increased two percent during the fiscal year although transaction accounts declined three percent. Our net interest margin exceeded three percent for the year, reaching 3.09 percent1% for the fiscal year. Total deposits increased 2% during the fiscal year although transaction accounts declined 3%. Our net interest margin exceeded 3% for the year, reaching 3.09%, driven primarily by the repricing of Federal Home Loan Bank advances to lower rates as they matured. Despite inflationary pressures, operating expenses increased by less than one percent1% for the fiscal year. Finally, we recorded no loan charge-offs during fiscal 2026 — our eighth consecutive year without reporting a net charge-off.
Returning capital to our shareholders is a priority. During fiscal 2026, we maintained our quarterly cash dividend of $0.14 per share and increased our share repurchases to approximately 344,000 shares, compared to approximately 285,000 shares in fiscal 2025.
38Fiscal 2027
As we look to fiscal 2027, our priorities remain consistent: measured growth in loans and retail deposits; disciplined expense management; and sound capital management. We believe this approach is the right course in an economy that continues to expand, while recognizing the need to remain cautious amid ongoing market and geopolitical uncertainties. We expect to continue returning capital to shareholders through dividends and share repurchases while maintaining sufficient capital to support our business strategy and withstand potential losses under adverse conditions. We remain committed to single-family residential, multi-family, and commercial real estate mortgage lending as our primary sources of asset growth and our retail branch network will continue to serve as the primary source of the Bank’s funding.
A Final Word
This year, Provident proudly celebrates the 70th anniversary of its founding, serving the great city of Riverside and its surrounding communities. As the largest independent community bank headquartered in Riverside County, we are proud of our distinguished history as a trusted provider of banking services. Just as importantly, we are proud of the commitment demonstrated throughout our organization to strengthen the communities we serve through volunteer service, charitable support and community investment. As we look to the year ahead and beyond, I want to assure you that the Board, management team and employees of Provident remain dedicated to carrying forward the Company’s reputation and legacy, just as we have since our founding. We will remain true to our community banking roots and focus on serving the families and small businesses of the Inland Empire. That heritage is central to who we are, and we intend to build on it in the years to come.
154In closing, I want to recognize and thank our employees and Directors for their commitment and service to Provident. Their efforts make our success possible. I also extend my sincere appreciation to our customers, shareholders, and the communities we serve for the confidence you place in us. Our continued success depends on the trust you place in Provident, and we are grateful for the opportunity to serve you.
68Sincerely,
/s/ Craig G. Blunden
Craig G. Blunden
Chairman of the Board of Directors
Financial Highlights
The following tables set forth information concerning the consolidated financial position and results of operations of the Corporation and its subsidiary at the dates and for the periods indicated.
| (In Thousands, Except Per Share Information) | 2026 | 2025 | 2024 | 2023 | 2022 |
|---|---|---|---|---|---|
| FINANCIAL CONDITION DATA: | |||||
| Total assets | $1,208,161 | $1,245,613 | $1,272,200 | $1,332,948 | $1,187,038 |
| Loans held for investment, net | 1,032,682 | 1,045,745 | 1,052,979 | 1,077,629 | 939,992 |
| Cash and cash equivalents | 49,210 | 53,090 | 51,376 | 65,849 | 23,414 |
| Investment securities | 90,523 | 111,006 | 131,900 | 156,492 | 188,421 |
| Deposits | 910,383 | 888,772 | 888,348 | 950,571 | 955,504 |
| Borrowings | 157,046 | 213,073 | 238,500 | 235,009 | 85,000 |
| Stockholders’ equity | 126,220 | 128,545 | 129,941 | 129,687 | 128,650 |
| Book value per share | 20.15 | 19.54 | 18.98 | 18.41 | 17.66 |
| OPERATING DATA: | |||||
| Interest income | $55,889 | $56,624 | $54,730 | $45,992 | $34,730 |
| Interest expense | 19,561 | 21,155 | 19,807 | 9,007 | 3,135 |
| Net interest income | 36,328 | 35,469 | 34,923 | 36,985 | 31,595 |
| (Recovery of) provision for credit losses | (553) | (666) | (63) | 374 | (2,462) |
| Net interest income after (recovery of) provision for credit losses | 36,881 | 36,135 | 34,986 | 36,611 | 34,057 |
| Loan servicing and other fees | 583 | 419 | 337 | 414 | 1,056 |
| Deposit account fees | 1,067 | 1,112 | 1,154 | 1,296 | 1,302 |
| Card and processing fees | 1,203 | 1,265 | 1,384 | 1,525 | 1,639 |
| Other non-interest income | 873 | 735 | 1,066 | 840 | 719 |
| Operating expenses | 30,971 | 30,793 | 28,540 | 28,270 | 25,915 |
| Income before income taxes | 9,636 | 8,873 | 10,387 | 12,416 | 12,858 |
| Provision for income taxes | 2,981 | 2,618 | 3,036 | 3,824 | 3,765 |
| Net income | $6,655 | $6,255 | $7,351 | $8,592 | $9,093 |
| Basic earnings per share | $1.04 | $0.93 | $1.06 | $1.20 | $1.23 |
| Diluted earnings per share | $1.03 | $0.93 | $1.06 | $1.19 | $1.22 |
| Cash dividend per share | $0.56 | $0.56 | $0.56 | $0.56 | $0.56 |
แก้ไขภายในรายงานประจำปี ไม่ใช่การคัดลอกข้อความที่เขียนใหม่มาแปะ
เครื่องมือ AI ส่วนใหญ่จะคืนจดหมายกลับมาเป็นข้อความแชท แล้วให้เราคัดลอกไปแปะในรายงานอีกที แต่ ทำงานในไฟล์ Word นั้นโดยตรง ไม่แตะต้องตัวเลขและตาราง พร้อมทั้งมีรายงานการติดตามการเปลี่ยนแปลงแสดงทุกจุดที่แก้ไขให้ผู้ตรวจสอบดู
อ่านต่อ
อ่านตัวอย่างการใช้งานจริงอีกเรื่อง
การตลาดและการสื่อสาร
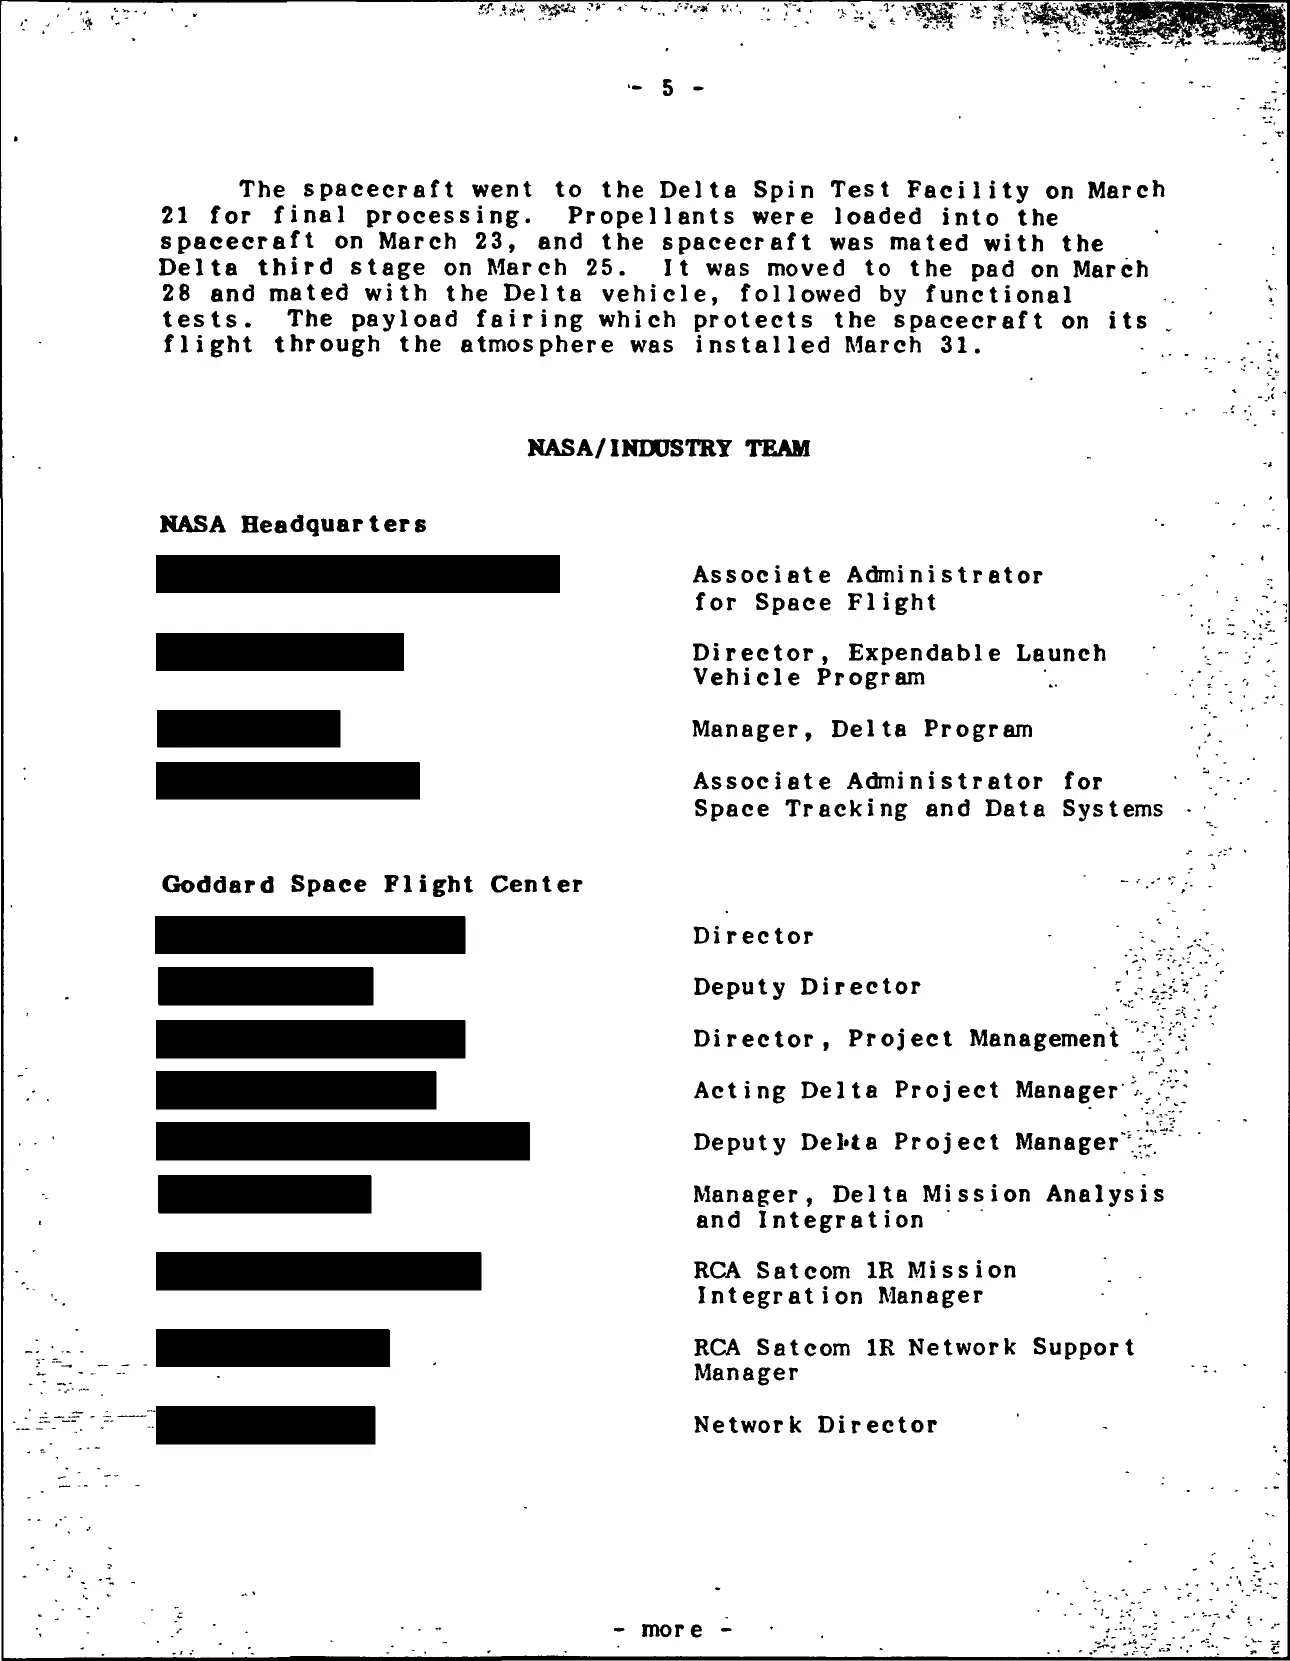
ชุดข้อมูลข่าว NASA ปี 1983 ที่สแกนและเซ็นเซอร์ จากนั้นเปิดเผยบางส่วน
การแพทย์
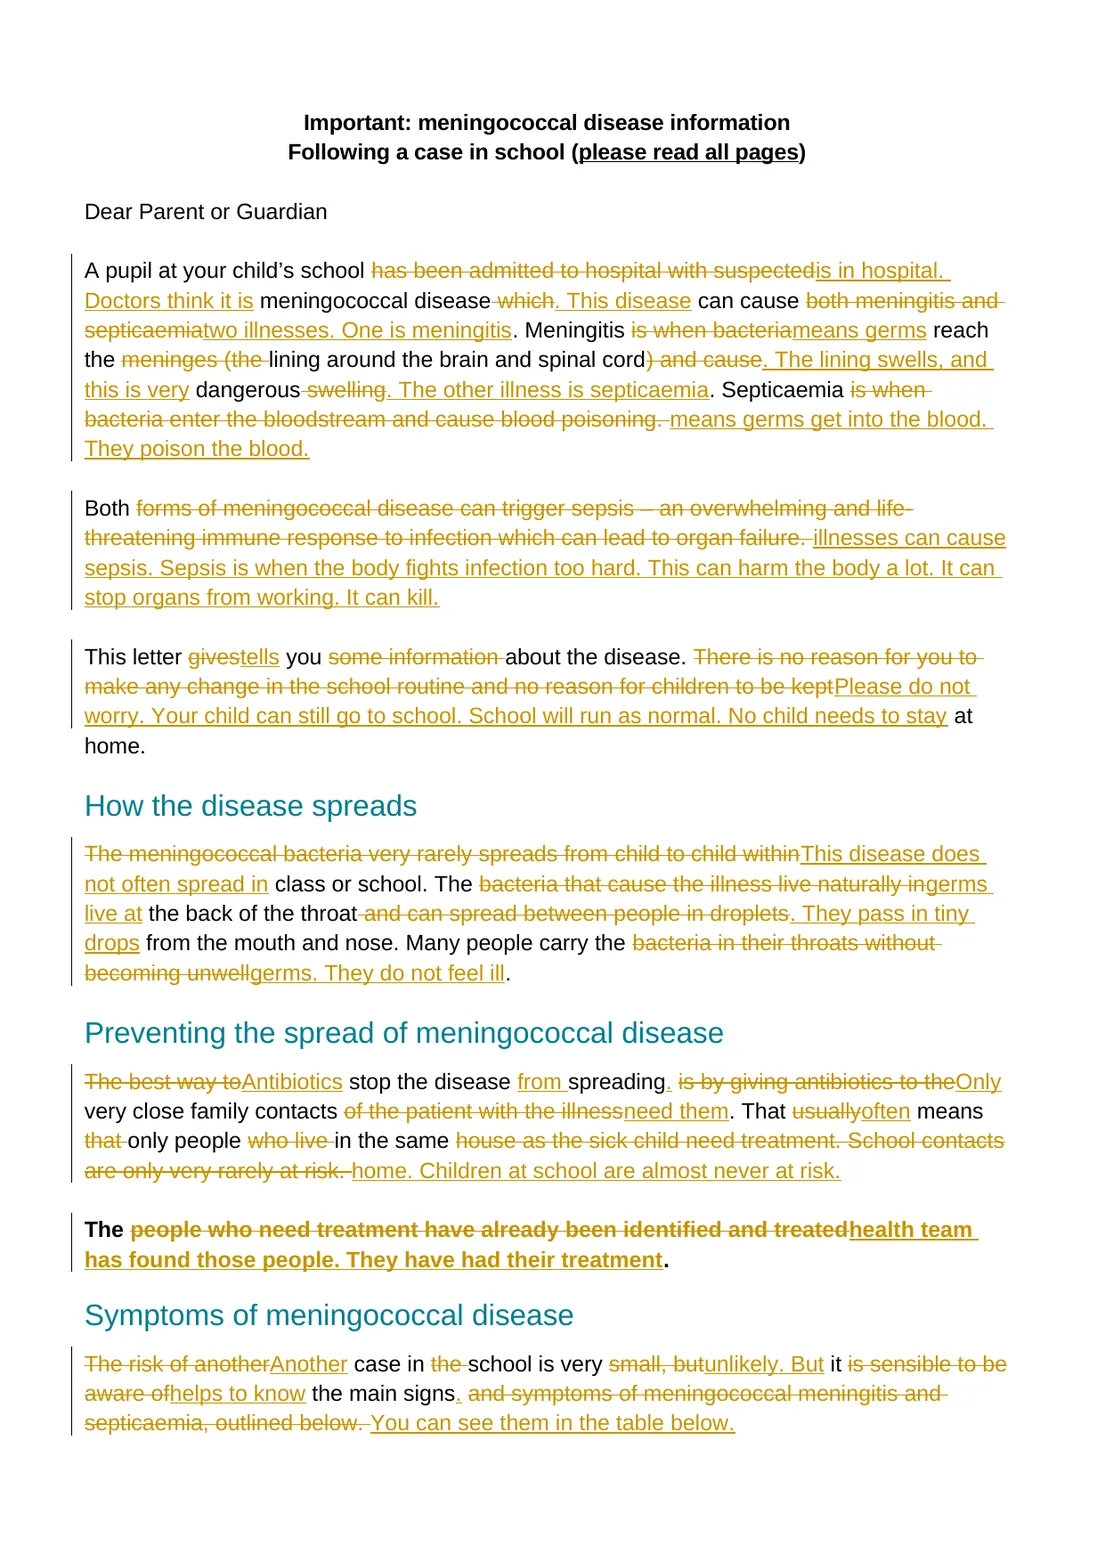
จดหมายสุขภาพถึงผู้ปกครองที่ทำให้ง่ายขึ้นด้วยการติดตามการเปลี่ยนแปลง จากนั้นแปลเป็นภาษาโปแลนด์
นายธนาคารและที่ปรึกษา
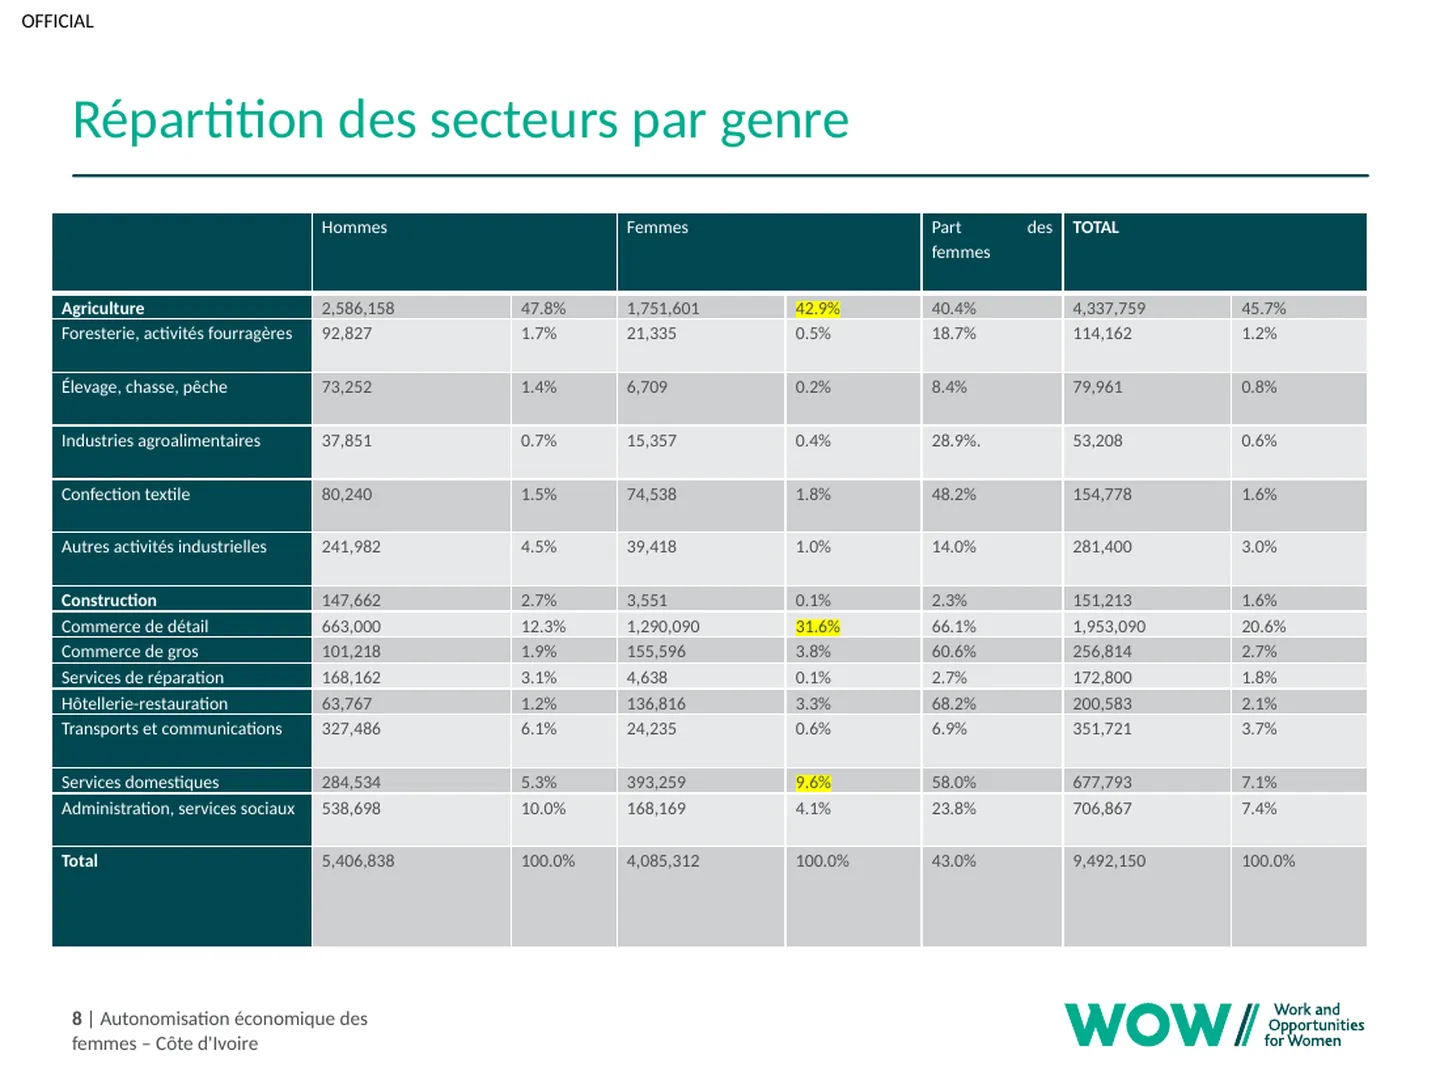
สไลด์งานพัฒนา 23 หน้าเป็นภาษาฝรั่งเศส แล้วแก้สามจุด
ดูตัวอย่างการใช้งานจริงทั้ง 19 เรื่อง →ตัวอย่างทั้งหมดสำหรับ การตลาดและการสื่อสาร →