ESEMPIO PRATICO · REVISIONE IN WORD
Lettera del presidente revisionata, poi ridotta a una versione web di 600 parole
Un addetto alle comunicazioni di una banca locale ha ricevuto il rapporto annuale come file Word. Ha chiesto a di correggere la lettera del presidente in stile AP, in modo leggero, senza toccare le cifre, una citazione della lettera dell'anno scorso o le tabelle finanziarie.
ha corretto un modificatore errato, ha migliorato la formulazione e ha unito tre frasi che la conversione del file aveva spezzato, il tutto nello stesso file, lasciando inalterata ogni singola cifra. Dopodiché ha ridotto la lettera da 1.093 a 600 parole per il web, scrivendo le percentuali in cifre e mantenendo integralmente la sezione finale.
1Il caricamento: il rapporto annuale della banca, come file Word
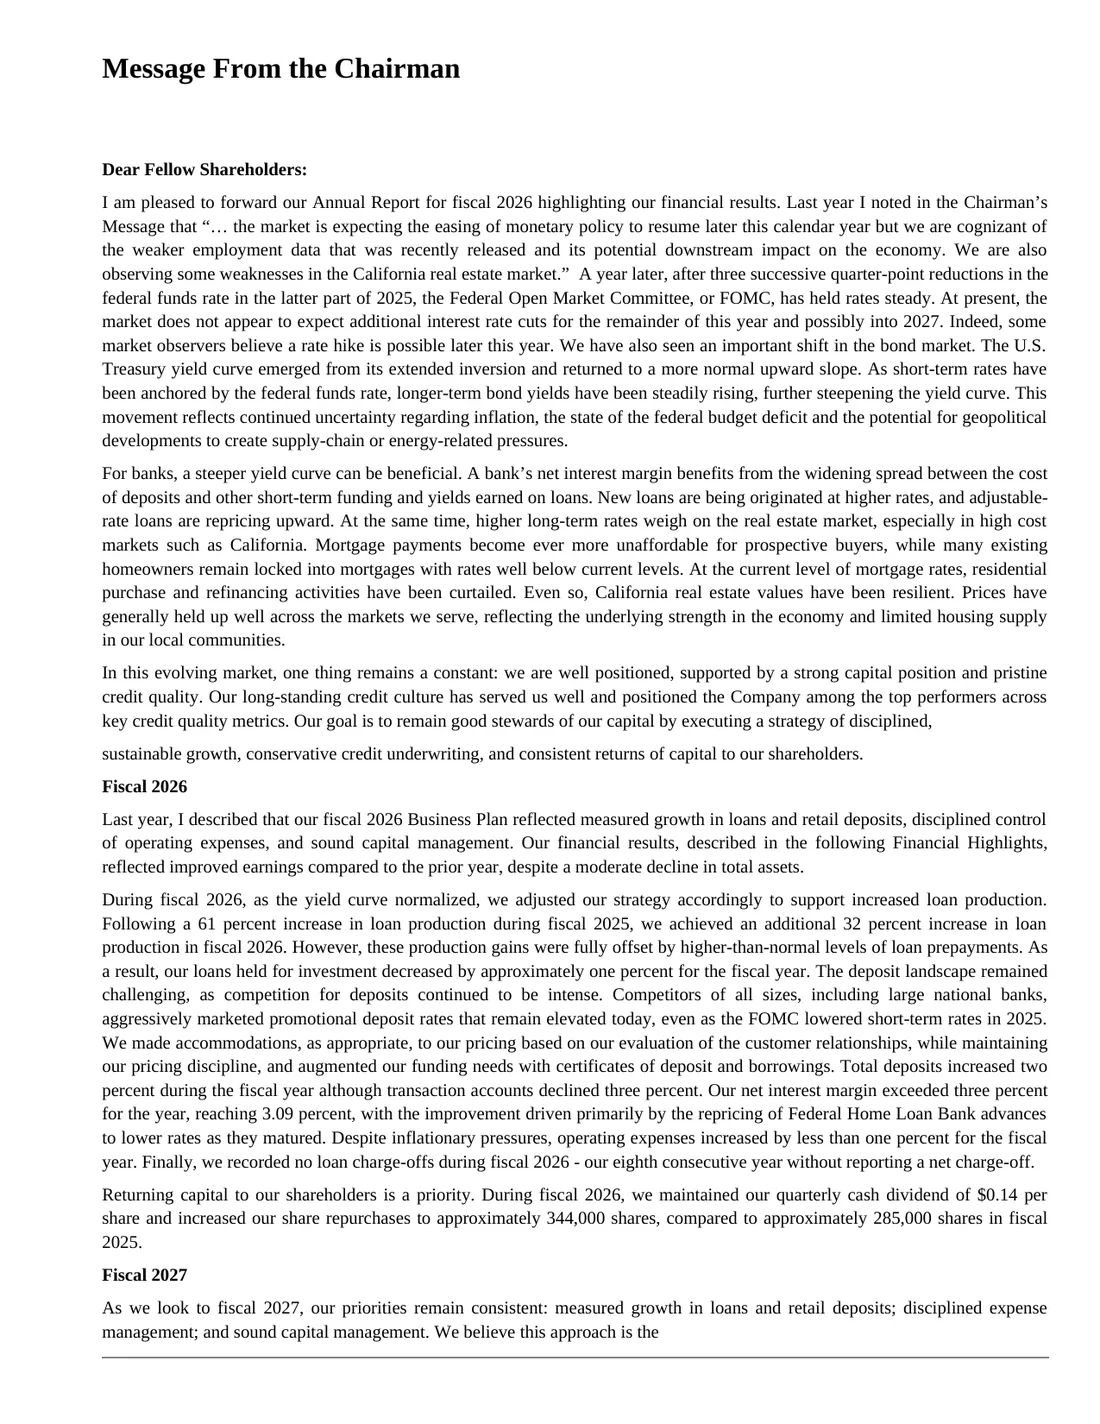
Message From the Chairman
Dear Fellow Shareholders:
Fiscal 2026
Fiscal 2027
A Final Word
Sincerely,
Financial Highlights
- 1,093 → 600parole nella lettera dopo la richiesta 2
- 3frasi spezzate e nuovamente unite
- 8cifre scritte «percento» convertite in %, valori mantenuti
- 0modifiche esterne alla lettera
Apri i file originali
Questi sono i file effettivi dell'esecuzione. Scaricali e aprili in Word.
Da dove proviene il file: Provident Financial Holdings, Inc., Rapporto annuale 2026 agli azionisti, depositato presso la SEC come Allegato 13 al Modulo 10-K. Un deposito pubblico; il testo appartiene alla società.
01 · IL FILE DI PARTENZA
Un rapporto annuale di 9 pagine, lettera a pagina 2
Il file è il rapporto annuale di una piccola banca quotata destinato ai suoi azionisti: una copertina, la lettera del presidente, le tabelle dei dati finanziari principali, le informazioni per gli azionisti, il consiglio di amministrazione e l'elenco delle filiali. Nove pagine e sei tabelle in un unico file Word.
Questo file Word è stato ricavato dal deposito pubblico SEC, una pagina web, tramite LibreOffice. La conversione ha suddiviso tre frasi in due paragrafi ciascuna, un difetto comune quando una pagina web diventa un file Word. Il prompt indica tutti e tre i punti.
02 · RICHIESTA 1
Rileggi la lettera, in stile AP, e mantieni le modifiche leggere
Cosa ha digitato l'addetto alle comunicazioni
Please proofread the 'Message From the Chairman' (from 'Dear Fellow Shareholders:' down to Craig Blunden's signature block) with tracked changes, AP style.

- Fix grammar, punctuation and awkward phrasing, but keep the edits light.
- Don't change any figures or the meaning. Leave the way numbers are written ('61 percent', 'one percent') alone for now.
- The quotation from last year's letter in the first paragraph ('… the market is expecting … California real estate market.') must stay word for word.
- Three sentences were split into two paragraphs when the file was converted: after 'disciplined,', after 'this approach is the', and after 'the year ahead and beyond,'. Join each back into one paragraph.
- Don't touch the Financial Highlights tables or anything after the letter.
Cosa ha fatto
- La lettera è stata modificata all'interno del file Word caricato. Il testo di tutte le altre pagine è rimasto invariato.
- È stato corretto un modificatore errato: "As the largest independent community bank headquartered in Riverside County, I am proud" ora diventa "we are proud", qui e nella frase successiva.
- Sono state apportate leggere correzioni in stile AP: "high-cost markets" con il trattino, un em dash spaziato in "fiscal 2026 — our eighth consecutive year", e "remains constant" al posto di "remains a constant".
- Sono state migliorate formulazioni poco scorrevoli, come "Last year, I said" al posto di "Last year, I described that", e sono state eliminate alcune parole superflue.
- Le tre frasi divise sono state nuovamente unite in un unico paragrafo ciascuna.
- La citazione della lettera dell'anno precedente, ogni singola cifra e il modo in cui ciascun numero è scritto sono stati lasciati esattamente come in origine.
La richiesta specificava di tracciare le modifiche, ma ha scritto le correzioni direttamente nel file, quindi il confronto sottostante proviene dalla funzione "Crea report delle modifiche" di , eseguita sui file prima e dopo.
Message From the Chairman
Dear Fellow Shareholders:
I am pleased to forward our Annual Report for fiscal 2026 highlighting our financial results. Last year I noted in the Chairman’s Message that “… the market is expecting the easing of monetary policy to resume later this calendar year but we are cognizant of the weaker employment data that was recently released and its potential downstream impact on the economy. We are also observing some weaknesses in the California real estate market.” A year later, after three successive quarter-point reductions in the federal funds rate in the latter part of 2025, the Federal Open Market Committee, or FOMC, has held rates steady. At present, the market does not appear to expect additional interest rate cuts for the remainder of this year and possibly into 2027. Indeed, some market observers believe a rate hike is possible later this year. We have also seen an important shift in the bond market. The U.S. Treasury yield curve emerged from its extended inversion and returned to a more normal upward slope. As short-term rates have been anchored by the federal funds rate, longer-term bond yields have been steadily rising, further steepening the yield curve. This movement reflects continued uncertainty regarding inflation, the state of the federal budget deficit and the potential for geopolitical developments to create supply-chain or energy-related pressures.
For banks, a steeper yield curve can be beneficial. A bank’s net interest margin benefits from the widening spread between the cost of deposits and other short-term funding and yields earned on loans. New loans are being originated at higher rates, and adjustable-rate loans are repricing upward. At the same time, higher long-term rates weigh on the real estate market, especially in high -cost markets such as California. Mortgage payments have become ever moreincreasingly unaffordable for prospective buyers, while many existing homeowners remain locked into mortgages with rates well below current levels. At the current level of mortgage rates, residential purchase and refinancing activities have been curtailed. Even so, California real estate values have been resilient. Prices have generally held up well across the markets we serve, reflecting the underlying strength in the economy and limited housing supply in our local communities.
In this evolving market, one thing remains a constant: we are well positioned, supported by a strong capital position and pristine credit quality. Our long-standing credit culture has served us well and positioned the Company among the top performers across key credit quality metrics. Our goal is to remain good stewards of our capital by executing a strategy of disciplined, 
sustainable growth, conservative credit underwriting, and consistent returns of capital to our shareholders.
Fiscal 2026
Last year, I described thatsaid our fiscal 2026 Business Plan reflected measured growth in loans and retail deposits, disciplined control of operating expenses, and sound capital management. Our financial results, described in the following Financial Highlights, reflected improved earnings compared to the prior year, despite a moderate decline in total assets.
During fiscal 2026, as the yield curve normalized, we adjusted our strategy accordingly to support increased loan production. Following a 61 percent increase in loan production during fiscal 2025, we achieved an additional 32 percent increase in loan production in fiscal 2026. However, these production gains were fully offset by higher-than-normal levels of loan prepayments. As a result, our loans held for investment decreased by approximately one percent for the fiscal year. The deposit landscape remained challenging, as competition for deposits continued to be intense. Competitors of all sizes, including large national banks, aggressively marketed promotional deposit rates that remain elevated today, even as the FOMC lowered short-term rates in 2025. We made accommodations, as appropriate, to our pricing based on our evaluation of the customer relationships, while maintaining our pricing discipline, and augmented our funding needs with certificates of deposit and borrowings. Total deposits increased two percent during the fiscal year although transaction accounts declined three percent. Our net interest margin exceeded three percent for the year, reaching 3.09 percent, with the improvement driven primarily by the repricing of Federal Home Loan Bank advances to lower rates as they matured. Despite inflationary pressures, operating expenses increased by less than one percent for the fiscal year. Finally, we recorded no loan charge-offs during fiscal 2026 -— our eighth consecutive year without reporting a net charge-off.
Returning capital to our shareholders is a priority. During fiscal 2026, we maintained our quarterly cash dividend of $0.14 per share and increased our share repurchases to approximately 344,000 shares, compared to approximately 285,000 shares in fiscal 2025.
Fiscal 2027
As we look to fiscal 2027, our priorities remain consistent: measured growth in loans and retail deposits; disciplined expense management; and sound capital management. We believe this approach is the 
right course in an economy that continues to expand, while recognizing the need to remain cautious amid ongoing market and geopolitical uncertainties. We expect to continue returning capital to shareholders through dividends and share repurchases while maintaining sufficient capital to support our business strategy and withstand potential losses under adverse conditions. We remain committed to single-family residential, multi-family, and commercial real estate mortgage lending as our primary sources of asset growth and our retail branch network will continue to serve as the primary source of the Bank’s funding.
A Final Word
This year, Provident proudly celebrates the 70th anniversary of its founding, serving the great city of Riverside and its surrounding communities. As the largest independent community bank headquartered in Riverside County, I amwe are proud of our distinguished history as a trusted provider of banking services. Just as importantly, I amwe are proud of the commitment demonstrated throughout our organization to strengthen the communities we serve through volunteer service, charitable support and community investment. As we look to the year ahead and beyond, 
I want to assure you that the Board, management team and employees of Provident remain dedicated to carrying forward the Company’s reputation and legacy, just as we have since our founding. We will remain true to our community banking roots and focus on serving the families and small businesses of the Inland Empire. That heritage is central to who we are, and we intend to build on it in the years to come.
In closing, I would likewant to recognize and thank our employees and Directors for their commitment and service to Provident. Their efforts make our success possible. I also extend my sincere appreciation to our customers, shareholders, and the communities we serve for the confidence you place in us. Our continued success depends on the trust you place in Provident, and we are grateful for the opportunity to serve you.
Sincerely,
/s/ Craig G. Blunden
Craig G. Blunden
Chairman of the Board of Directors
03 · RICHIESTA 2
Ora taglialo a circa 600 parole per il web
Cosa ha digitato l'addetto alle comunicazioni
Thanks. Please accept all of your tracked changes, then turn the letter into the web version in the same file, again with tracked changes so Craig can see what was cut:
1. Switch percentages to numerals with % (61%, 32%, 1%, 2%, 3%, 3.09%).
2. Cut the letter from about 1,100 words to about 600. Trim the interest-rate and real-estate commentary in the opening paragraphs first.
3. Keep the 'A Final Word' section in full.
4. Any figure that stays must keep its value. Financial Highlights stays untouched.
Cosa ha fatto
- Il lavoro è continuato all'interno del file Word consegnato per la richiesta 1.
- La lettera è stata ridotta da 1.082 a 600 parole. La maggior parte dei tagli è derivata dall'introduzione sui tassi d'interesse, sul mercato obbligazionario e sul settore immobiliare della California, come richiesto: quei tre paragrafi sono passati da 429 a 63 parole.
- Sono state inoltre accorciate le frasi sulla concorrenza sui depositi nella sezione "Fiscal 2026" e l'ultima frase nella sezione "Fiscal 2027".
- Ogni percentuale è stata scritta in cifre con il simbolo %: 61%, 32%, 1%, 2%, 3% e 3,09%, mantenendo gli stessi valori di prima.
- Sezione "A Final Word" lasciata parola per parola e tabelle "Financial Highlights" intatte.
Anche in questo caso le modifiche sono state inserite direttamente nel file. Le revisioni evidenziate provengono dal report delle modifiche sui file delle richieste 1 e 2, con il conteggio delle parole di ciascun paragrafo a margine.
Message From the Chairman
Dear Fellow Shareholders:
I am pleased to forward our Annual Report for fiscal 2026 highlighting our financial results. Last year I noted in the Chairman’s Message that “… the market is expecting the easing of monetary policy to resume later this calendar year but we are cognizant of the weaker employment data that was recently released and its potential downstream impact on the economy. We are also observing some weaknesses in the California real estate market.” A year later, after three successive quarter-point reductions in the federal funds rate in the latter part of 2025, the Federal Open Market Committee, or FOMC, has held rates steady. At present, the market does not appear to expect additional interest rate cuts for the remainder of this year and possibly into 2027. Indeed, some market observers believe a rate hike is possible later this year. We have also seen an important shift in the bond market. The U.S. Treasury yield curve emerged from its extended inversion and returned to a more normal upward slope. As short-term rates have been anchored by the federal funds rate, longer-term bond yields have been steadily rising, further steepening the yield curve. This movement reflects continued uncertainty regarding inflation, the state of the federal budget deficit and the potential for geopolitical developments to create supply-chain or energy-related pressures.
For banks, a steeper yield curve can be beneficial. A bank’s net interest margin benefits from the widening spread between the cost of deposits and other short-term funding and yields earned on loans. New loans are being originated at higher rates, and adjustable-rate loans are repricing upward. At the same time, higher long-term rates weigh on the real estate market, especially in high-cost markets such as California. Mortgage payments have become increasingly unaffordable for prospective buyers, while many existing homeowners remain locked into mortgages with rates well below current levels. At the current level of mortgage rates, residential purchase and refinancing activities have been curtailed. Even so, California real estate values have been resilient. Prices have generally held up well across the markets we serve, reflecting the underlying strength in the economy and limited housing supply in our local communities.
In this evolving market, one thing remains constant: we are well positioned, supported by a strong capital position and pristine credit quality. Our long-standing credit culture has served us well and positioned the Company among the top performers across key credit quality metrics. Our goal is to remain good stewards of our capital by executing a strategy of disciplined, sustainable growth, conservative credit underwriting, and consistent returns of capital to our shareholders.
Fiscal 2026
Last year, I said our fiscal 2026 Business Plan reflected measured growth in loans and retail deposits, disciplined control of operating expenses, and sound capital management. Our financial results, described in the following Financial Highlights, reflected improved earnings compared to the prior year, despite a moderate decline in total assets.
50During fiscal 2026, as the yield curve normalized, we adjusted our strategy to support increased loan production. Following a 61 percent% increase in loan production during fiscal 2025, we achieved an additional 32 percent% increase in fiscal 2026. However, these production gains were fully offset by higher-than-normal levels of loan prepayments. As a result, our loans held for investment decreased by approximately one percent for the fiscal year. The deposit landscape remained challenging, as competition for deposits continued to be intense. Competitors of all sizes, including large national banks, aggressively marketed promotional deposit rates that remain elevated today, even as the FOMC lowered short-term rates in 2025. We made accommodations, as appropriate, to our pricing based on our evaluation of the customer relationships, while maintaining our pricing discipline, and augmented our funding needs with certificates of deposit and borrowings. Total deposits increased two percent during the fiscal year although transaction accounts declined three percent. Our net interest margin exceeded three percent for the year, reaching 3.09 percent1% for the fiscal year. Total deposits increased 2% during the fiscal year although transaction accounts declined 3%. Our net interest margin exceeded 3% for the year, reaching 3.09%, driven primarily by the repricing of Federal Home Loan Bank advances to lower rates as they matured. Despite inflationary pressures, operating expenses increased by less than one percent1% for the fiscal year. Finally, we recorded no loan charge-offs during fiscal 2026 — our eighth consecutive year without reporting a net charge-off.
Returning capital to our shareholders is a priority. During fiscal 2026, we maintained our quarterly cash dividend of $0.14 per share and increased our share repurchases to approximately 344,000 shares, compared to approximately 285,000 shares in fiscal 2025.
38Fiscal 2027
As we look to fiscal 2027, our priorities remain consistent: measured growth in loans and retail deposits; disciplined expense management; and sound capital management. We believe this approach is the right course in an economy that continues to expand, while recognizing the need to remain cautious amid ongoing market and geopolitical uncertainties. We expect to continue returning capital to shareholders through dividends and share repurchases while maintaining sufficient capital to support our business strategy and withstand potential losses under adverse conditions. We remain committed to single-family residential, multi-family, and commercial real estate mortgage lending as our primary sources of asset growth and our retail branch network will continue to serve as the primary source of the Bank’s funding.
A Final Word
This year, Provident proudly celebrates the 70th anniversary of its founding, serving the great city of Riverside and its surrounding communities. As the largest independent community bank headquartered in Riverside County, we are proud of our distinguished history as a trusted provider of banking services. Just as importantly, we are proud of the commitment demonstrated throughout our organization to strengthen the communities we serve through volunteer service, charitable support and community investment. As we look to the year ahead and beyond, I want to assure you that the Board, management team and employees of Provident remain dedicated to carrying forward the Company’s reputation and legacy, just as we have since our founding. We will remain true to our community banking roots and focus on serving the families and small businesses of the Inland Empire. That heritage is central to who we are, and we intend to build on it in the years to come.
154In closing, I want to recognize and thank our employees and Directors for their commitment and service to Provident. Their efforts make our success possible. I also extend my sincere appreciation to our customers, shareholders, and the communities we serve for the confidence you place in us. Our continued success depends on the trust you place in Provident, and we are grateful for the opportunity to serve you.
68Sincerely,
/s/ Craig G. Blunden
Craig G. Blunden
Chairman of the Board of Directors
Financial Highlights
The following tables set forth information concerning the consolidated financial position and results of operations of the Corporation and its subsidiary at the dates and for the periods indicated.
| (In Thousands, Except Per Share Information) | 2026 | 2025 | 2024 | 2023 | 2022 |
|---|---|---|---|---|---|
| FINANCIAL CONDITION DATA: | |||||
| Total assets | $1,208,161 | $1,245,613 | $1,272,200 | $1,332,948 | $1,187,038 |
| Loans held for investment, net | 1,032,682 | 1,045,745 | 1,052,979 | 1,077,629 | 939,992 |
| Cash and cash equivalents | 49,210 | 53,090 | 51,376 | 65,849 | 23,414 |
| Investment securities | 90,523 | 111,006 | 131,900 | 156,492 | 188,421 |
| Deposits | 910,383 | 888,772 | 888,348 | 950,571 | 955,504 |
| Borrowings | 157,046 | 213,073 | 238,500 | 235,009 | 85,000 |
| Stockholders’ equity | 126,220 | 128,545 | 129,941 | 129,687 | 128,650 |
| Book value per share | 20.15 | 19.54 | 18.98 | 18.41 | 17.66 |
| OPERATING DATA: | |||||
| Interest income | $55,889 | $56,624 | $54,730 | $45,992 | $34,730 |
| Interest expense | 19,561 | 21,155 | 19,807 | 9,007 | 3,135 |
| Net interest income | 36,328 | 35,469 | 34,923 | 36,985 | 31,595 |
| (Recovery of) provision for credit losses | (553) | (666) | (63) | 374 | (2,462) |
| Net interest income after (recovery of) provision for credit losses | 36,881 | 36,135 | 34,986 | 36,611 | 34,057 |
| Loan servicing and other fees | 583 | 419 | 337 | 414 | 1,056 |
| Deposit account fees | 1,067 | 1,112 | 1,154 | 1,296 | 1,302 |
| Card and processing fees | 1,203 | 1,265 | 1,384 | 1,525 | 1,639 |
| Other non-interest income | 873 | 735 | 1,066 | 840 | 719 |
| Operating expenses | 30,971 | 30,793 | 28,540 | 28,270 | 25,915 |
| Income before income taxes | 9,636 | 8,873 | 10,387 | 12,416 | 12,858 |
| Provision for income taxes | 2,981 | 2,618 | 3,036 | 3,824 | 3,765 |
| Net income | $6,655 | $6,255 | $7,351 | $8,592 | $9,093 |
| Basic earnings per share | $1.04 | $0.93 | $1.06 | $1.20 | $1.23 |
| Diluted earnings per share | $1.03 | $0.93 | $1.06 | $1.19 | $1.22 |
| Cash dividend per share | $0.56 | $0.56 | $0.56 | $0.56 | $0.56 |
Modifiche all'interno del rapporto annuale, non una riscrittura incollata
La maggior parte degli strumenti di IA restituisce la lettera sotto forma di testo in chat e qualcuno deve incollarla nuovamente nel rapporto. lavora direttamente nel file Word, non tocca le cifre e le tabelle, e il report delle modifiche tracciate mostra al revisore ogni singola modifica.
CONTINUA A LEGGERE
Leggi un altro esempio pratico
Marketing e comunicazione
Cartella stampa della NASA del 1983 scansionata e censurata, poi parzialmente svelata
Sanità
Una lettera sulla salute per i genitori semplificata con tracciamento delle modifiche, poi in polacco
Bancari e consulenti
Una presentazione sullo sviluppo di 23 slide in francese, poi tre correzioni
Vedi tutti i 19 esempi pratici →Tutti gli esempi per Marketing e comunicazione →