דוגמת עבודה · הגהה ב-WORD
מכתב היושב-ראש עבר הגהה ואז קוצר לגרסת אינטרנט בת 600 מילים
קצין תקשורת בבנק קהילתי קיבל את הדוח השנתי כקובץ Word. הוא ביקש מ- להגיה את מכתב היושב-ראש בסגנון AP, בקלילות, מבלי לגעת במספרים, בציטוט ממכתב השנה שעברה או בטבלאות הפיננסיות.
תיקן פתיחה תלויה, החליק ניסוחים מגושמים וחיבר שלושה משפטים שפיצלה המרת הקובץ, הכל באותו קובץ, והשאיר כל מספר כפי שנכתב. לאחר מכן הוא קיצץ את המכתב מ-1,093 ל-600 מילים לאינטרנט, כתב אחוזים כמספרים ושמר על קטע הסיום במלואו.
1ההעלאה: הדוח השנתי של הבנק, כקובץ Word
Message From the Chairman
Dear Fellow Shareholders:
Fiscal 2026
Fiscal 2027
A Final Word
Sincerely,
Financial Highlights
- 1,093 → 600מילים במכתב לאחר בקשה 2
- 3משפטים מפוצלים חוברו מחדש
- 8נתוני "אחוז" שונו ל-%, הערכים נשמרו
- 0עריכות מחוץ למכתב
פתח את הקבצים האמיתיים
אלו הקבצים המקוריים מהריצה. הורד אותם ופתח אותם ב-Word.
מאיפה מגיע הקובץ: Provident Financial Holdings, Inc., דוח שנתי 2026 לבעלי המניות, הוגש לרשות לניירות ערך (SEC) כנספח 13 לטופס 10-K. הגשה ציבורית; הטקסט שייך לחברה.
01 · קובץ ההתחלה
דוח שנתי בן 9 עמודים, המכתב בעמוד 2
הקובץ הוא הדוח השנתי של בנק קטן הנסחר בבורסה לבעלי המניות שלו: שער, מכתב היושב-ראש, לאחר מכן טבלאות Financial Highlights, מידע לבעלי מניות, הדירקטוריון ורשימת הסניפים. תשעה עמודים ושש טבלאות בקובץ Word אחד.
יצרנו קובץ Word זה מהגשת ה-SEC הציבורית, דף אינטרנט, באמצעות LibreOffice. ההמרה פיצלה שלושה משפטים לשתי פסקאות כל אחד, תקלה נפוצה כאשר דף אינטרנט הופך לקובץ Word. הבקשה מציינת את שלושת המקומות.
02 · בקשה 1
"הגה את המכתב בסגנון AP, ושמור על עריכה קלה"
מה שקצין התקשורת הקליד
Please proofread the 'Message From the Chairman' (from 'Dear Fellow Shareholders:' down to Craig Blunden's signature block) with tracked changes, AP style.

- Fix grammar, punctuation and awkward phrasing, but keep the edits light.
- Don't change any figures or the meaning. Leave the way numbers are written ('61 percent', 'one percent') alone for now.
- The quotation from last year's letter in the first paragraph ('… the market is expecting … California real estate market.') must stay word for word.
- Three sentences were split into two paragraphs when the file was converted: after 'disciplined,', after 'this approach is the', and after 'the year ahead and beyond,'. Join each back into one paragraph.
- Don't touch the Financial Highlights tables or anything after the letter.
מה ש- עשה
- ערך את המכתב בתוך קובץ ה-Word שהועלה. הטקסט של שאר העמודים לא השתנה.
- תיקן פתיחה תלויה: "As the largest independent community bank headquartered in Riverside County, I am proud" קורא כעת "we are proud", כאן ובמשפט הבא.
- ביצע תיקוני AP קלילים: "high-cost markets" עם מקף, מקף אמצעי מרווח ב-"fiscal 2026 — our eighth consecutive year", ו-"remains constant" במקום "remains a constant".
- החליק ניסוחים מגושמים, כגון "Last year, I said" עבור "Last year, I described that", והסיר מספר מילים שהמשפטים לא נזקקו להן.
- חיבר את שלושת המשפטים המפוצלים חזרה לפסקה אחת כל אחד.
- השאיר את הציטוט ממכתב השנה שעברה, כל מספר והאופן שבו כל מספר נכתב בדיוק כפי שהיו.
הבקשה דרשה מעקב שינויים, אך כתב את העריכות ישירות לקובץ, ולכן סימוני השינויים האדומים להלן מגיעים מהפונקציה “יצירת דוח מעקב שינויים” של , שהורצה על הקובצים לפני ואחרי.
Message From the Chairman
Dear Fellow Shareholders:
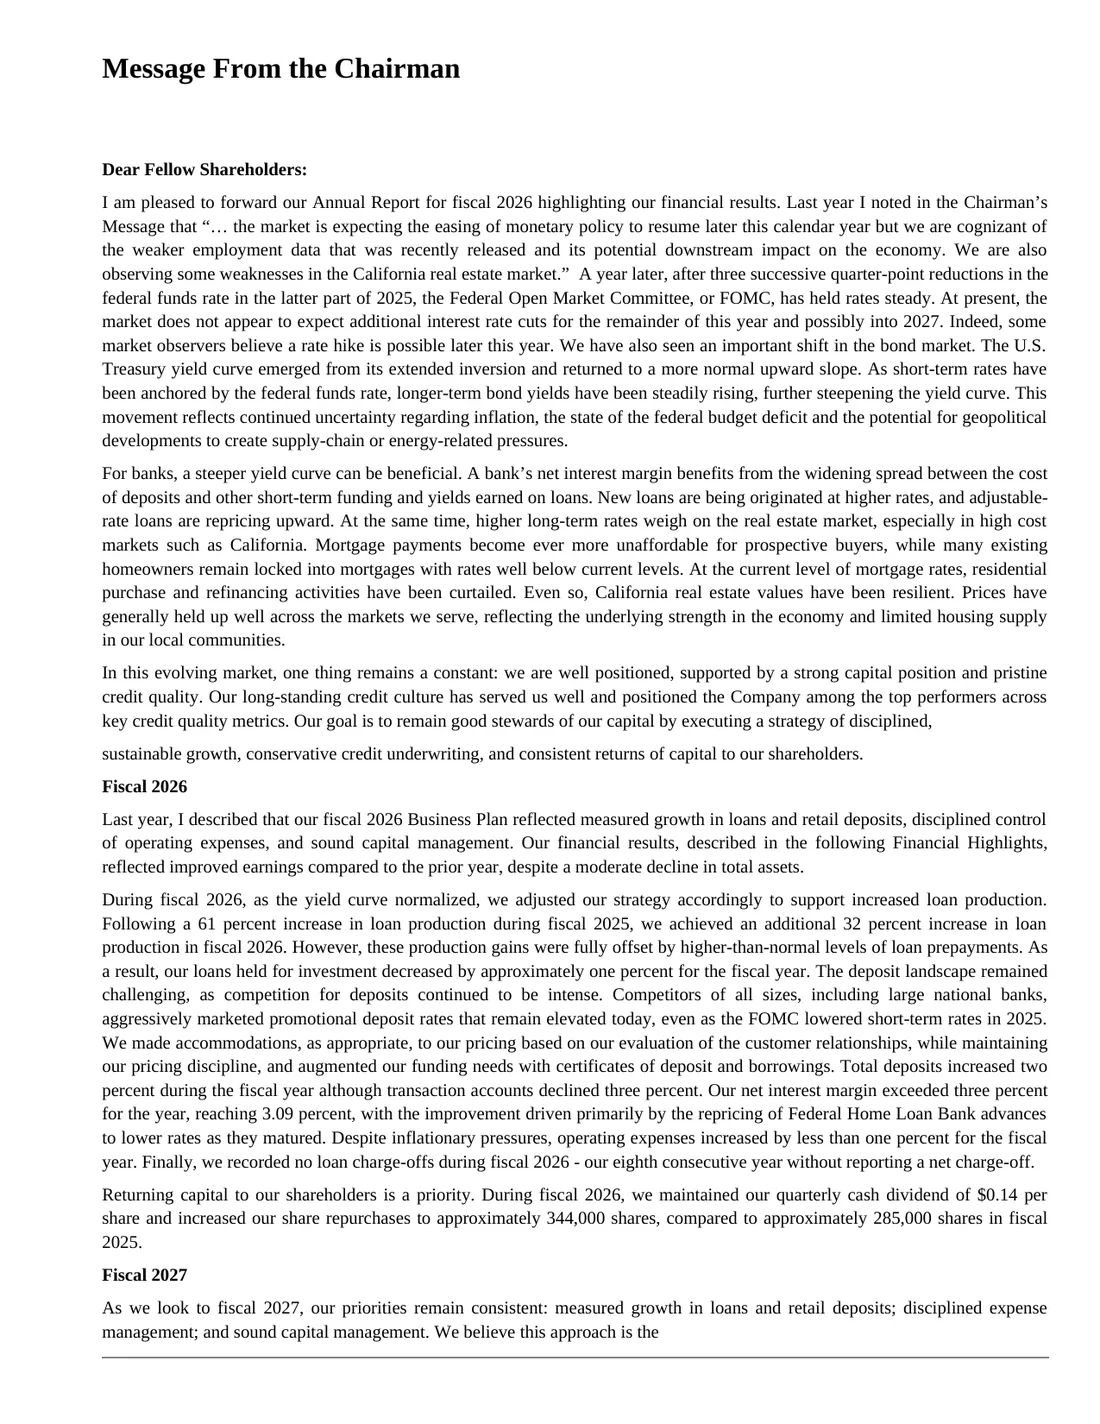
I am pleased to forward our Annual Report for fiscal 2026 highlighting our financial results. Last year I noted in the Chairman’s Message that “… the market is expecting the easing of monetary policy to resume later this calendar year but we are cognizant of the weaker employment data that was recently released and its potential downstream impact on the economy. We are also observing some weaknesses in the California real estate market.” A year later, after three successive quarter-point reductions in the federal funds rate in the latter part of 2025, the Federal Open Market Committee, or FOMC, has held rates steady. At present, the market does not appear to expect additional interest rate cuts for the remainder of this year and possibly into 2027. Indeed, some market observers believe a rate hike is possible later this year. We have also seen an important shift in the bond market. The U.S. Treasury yield curve emerged from its extended inversion and returned to a more normal upward slope. As short-term rates have been anchored by the federal funds rate, longer-term bond yields have been steadily rising, further steepening the yield curve. This movement reflects continued uncertainty regarding inflation, the state of the federal budget deficit and the potential for geopolitical developments to create supply-chain or energy-related pressures.
For banks, a steeper yield curve can be beneficial. A bank’s net interest margin benefits from the widening spread between the cost of deposits and other short-term funding and yields earned on loans. New loans are being originated at higher rates, and adjustable-rate loans are repricing upward. At the same time, higher long-term rates weigh on the real estate market, especially in high -cost markets such as California. Mortgage payments have become ever moreincreasingly unaffordable for prospective buyers, while many existing homeowners remain locked into mortgages with rates well below current levels. At the current level of mortgage rates, residential purchase and refinancing activities have been curtailed. Even so, California real estate values have been resilient. Prices have generally held up well across the markets we serve, reflecting the underlying strength in the economy and limited housing supply in our local communities.
In this evolving market, one thing remains a constant: we are well positioned, supported by a strong capital position and pristine credit quality. Our long-standing credit culture has served us well and positioned the Company among the top performers across key credit quality metrics. Our goal is to remain good stewards of our capital by executing a strategy of disciplined, 
sustainable growth, conservative credit underwriting, and consistent returns of capital to our shareholders.
Fiscal 2026
Last year, I described thatsaid our fiscal 2026 Business Plan reflected measured growth in loans and retail deposits, disciplined control of operating expenses, and sound capital management. Our financial results, described in the following Financial Highlights, reflected improved earnings compared to the prior year, despite a moderate decline in total assets.
During fiscal 2026, as the yield curve normalized, we adjusted our strategy accordingly to support increased loan production. Following a 61 percent increase in loan production during fiscal 2025, we achieved an additional 32 percent increase in loan production in fiscal 2026. However, these production gains were fully offset by higher-than-normal levels of loan prepayments. As a result, our loans held for investment decreased by approximately one percent for the fiscal year. The deposit landscape remained challenging, as competition for deposits continued to be intense. Competitors of all sizes, including large national banks, aggressively marketed promotional deposit rates that remain elevated today, even as the FOMC lowered short-term rates in 2025. We made accommodations, as appropriate, to our pricing based on our evaluation of the customer relationships, while maintaining our pricing discipline, and augmented our funding needs with certificates of deposit and borrowings. Total deposits increased two percent during the fiscal year although transaction accounts declined three percent. Our net interest margin exceeded three percent for the year, reaching 3.09 percent, with the improvement driven primarily by the repricing of Federal Home Loan Bank advances to lower rates as they matured. Despite inflationary pressures, operating expenses increased by less than one percent for the fiscal year. Finally, we recorded no loan charge-offs during fiscal 2026 -— our eighth consecutive year without reporting a net charge-off.
Returning capital to our shareholders is a priority. During fiscal 2026, we maintained our quarterly cash dividend of $0.14 per share and increased our share repurchases to approximately 344,000 shares, compared to approximately 285,000 shares in fiscal 2025.
Fiscal 2027
As we look to fiscal 2027, our priorities remain consistent: measured growth in loans and retail deposits; disciplined expense management; and sound capital management. We believe this approach is the 
right course in an economy that continues to expand, while recognizing the need to remain cautious amid ongoing market and geopolitical uncertainties. We expect to continue returning capital to shareholders through dividends and share repurchases while maintaining sufficient capital to support our business strategy and withstand potential losses under adverse conditions. We remain committed to single-family residential, multi-family, and commercial real estate mortgage lending as our primary sources of asset growth and our retail branch network will continue to serve as the primary source of the Bank’s funding.
A Final Word
This year, Provident proudly celebrates the 70th anniversary of its founding, serving the great city of Riverside and its surrounding communities. As the largest independent community bank headquartered in Riverside County, I amwe are proud of our distinguished history as a trusted provider of banking services. Just as importantly, I amwe are proud of the commitment demonstrated throughout our organization to strengthen the communities we serve through volunteer service, charitable support and community investment. As we look to the year ahead and beyond, 
I want to assure you that the Board, management team and employees of Provident remain dedicated to carrying forward the Company’s reputation and legacy, just as we have since our founding. We will remain true to our community banking roots and focus on serving the families and small businesses of the Inland Empire. That heritage is central to who we are, and we intend to build on it in the years to come.
In closing, I would likewant to recognize and thank our employees and Directors for their commitment and service to Provident. Their efforts make our success possible. I also extend my sincere appreciation to our customers, shareholders, and the communities we serve for the confidence you place in us. Our continued success depends on the trust you place in Provident, and we are grateful for the opportunity to serve you.
Sincerely,
/s/ Craig G. Blunden
Craig G. Blunden
Chairman of the Board of Directors
03 · בקשה 2
"כעת קצץ אותו לכ-600 מילים עבור האינטרנט"
מה שקצין התקשורת הקליד
Thanks. Please accept all of your tracked changes, then turn the letter into the web version in the same file, again with tracked changes so Craig can see what was cut:
1. Switch percentages to numerals with % (61%, 32%, 1%, 2%, 3%, 3.09%).
2. Cut the letter from about 1,100 words to about 600. Trim the interest-rate and real-estate commentary in the opening paragraphs first.
3. Keep the 'A Final Word' section in full.
4. Any figure that stays must keep its value. Financial Highlights stays untouched.
מה ש- עשה
- המשיך לעבוד בקובץ ה-Word שהוא סיפק עבור בקשה 1.
- קיצץ את המכתב מ-1,082 מילים ל-600. רוב הקיצוץ הגיע מהפתיחה על שיעורי הריבית, שוק האג"ח ונדל"ן בקליפורניה, כפי שנתבקש: שלוש הפסקאות הללו ירדו מ-429 מילים ל-63.
- המשפטים על תחרות הפיקדונות תחת "Fiscal 2026" והמשפט האחרון תחת "Fiscal 2027" קוצצו גם הם.
- כתב כל אחוז כמספר עם %: 61%, 32%, 1%, 2%, 3% ו-3.09%, באותם ערכים כמו קודם.
- השאיר את "A Final Word" מילה במילה, ואת טבלאות הנתונים הפיננסיים ללא נגיעה.
גם הפעם התיקונים בוצעו ישירות בקובץ. סימון השינויים הוא דוח מעקב השינויים על קובצי בקשה 1 ובקשה 2, עם ספירת המילים של כל פסקה בשוליים.
Message From the Chairman
Dear Fellow Shareholders:
I am pleased to forward our Annual Report for fiscal 2026 highlighting our financial results. Last year I noted in the Chairman’s Message that “… the market is expecting the easing of monetary policy to resume later this calendar year but we are cognizant of the weaker employment data that was recently released and its potential downstream impact on the economy. We are also observing some weaknesses in the California real estate market.” A year later, after three successive quarter-point reductions in the federal funds rate in the latter part of 2025, the Federal Open Market Committee, or FOMC, has held rates steady. At present, the market does not appear to expect additional interest rate cuts for the remainder of this year and possibly into 2027. Indeed, some market observers believe a rate hike is possible later this year. We have also seen an important shift in the bond market. The U.S. Treasury yield curve emerged from its extended inversion and returned to a more normal upward slope. As short-term rates have been anchored by the federal funds rate, longer-term bond yields have been steadily rising, further steepening the yield curve. This movement reflects continued uncertainty regarding inflation, the state of the federal budget deficit and the potential for geopolitical developments to create supply-chain or energy-related pressures.
For banks, a steeper yield curve can be beneficial. A bank’s net interest margin benefits from the widening spread between the cost of deposits and other short-term funding and yields earned on loans. New loans are being originated at higher rates, and adjustable-rate loans are repricing upward. At the same time, higher long-term rates weigh on the real estate market, especially in high-cost markets such as California. Mortgage payments have become increasingly unaffordable for prospective buyers, while many existing homeowners remain locked into mortgages with rates well below current levels. At the current level of mortgage rates, residential purchase and refinancing activities have been curtailed. Even so, California real estate values have been resilient. Prices have generally held up well across the markets we serve, reflecting the underlying strength in the economy and limited housing supply in our local communities.
In this evolving market, one thing remains constant: we are well positioned, supported by a strong capital position and pristine credit quality. Our long-standing credit culture has served us well and positioned the Company among the top performers across key credit quality metrics. Our goal is to remain good stewards of our capital by executing a strategy of disciplined, sustainable growth, conservative credit underwriting, and consistent returns of capital to our shareholders.
Fiscal 2026
Last year, I said our fiscal 2026 Business Plan reflected measured growth in loans and retail deposits, disciplined control of operating expenses, and sound capital management. Our financial results, described in the following Financial Highlights, reflected improved earnings compared to the prior year, despite a moderate decline in total assets.
50During fiscal 2026, as the yield curve normalized, we adjusted our strategy to support increased loan production. Following a 61 percent% increase in loan production during fiscal 2025, we achieved an additional 32 percent% increase in fiscal 2026. However, these production gains were fully offset by higher-than-normal levels of loan prepayments. As a result, our loans held for investment decreased by approximately one percent for the fiscal year. The deposit landscape remained challenging, as competition for deposits continued to be intense. Competitors of all sizes, including large national banks, aggressively marketed promotional deposit rates that remain elevated today, even as the FOMC lowered short-term rates in 2025. We made accommodations, as appropriate, to our pricing based on our evaluation of the customer relationships, while maintaining our pricing discipline, and augmented our funding needs with certificates of deposit and borrowings. Total deposits increased two percent during the fiscal year although transaction accounts declined three percent. Our net interest margin exceeded three percent for the year, reaching 3.09 percent1% for the fiscal year. Total deposits increased 2% during the fiscal year although transaction accounts declined 3%. Our net interest margin exceeded 3% for the year, reaching 3.09%, driven primarily by the repricing of Federal Home Loan Bank advances to lower rates as they matured. Despite inflationary pressures, operating expenses increased by less than one percent1% for the fiscal year. Finally, we recorded no loan charge-offs during fiscal 2026 — our eighth consecutive year without reporting a net charge-off.
Returning capital to our shareholders is a priority. During fiscal 2026, we maintained our quarterly cash dividend of $0.14 per share and increased our share repurchases to approximately 344,000 shares, compared to approximately 285,000 shares in fiscal 2025.
38Fiscal 2027
As we look to fiscal 2027, our priorities remain consistent: measured growth in loans and retail deposits; disciplined expense management; and sound capital management. We believe this approach is the right course in an economy that continues to expand, while recognizing the need to remain cautious amid ongoing market and geopolitical uncertainties. We expect to continue returning capital to shareholders through dividends and share repurchases while maintaining sufficient capital to support our business strategy and withstand potential losses under adverse conditions. We remain committed to single-family residential, multi-family, and commercial real estate mortgage lending as our primary sources of asset growth and our retail branch network will continue to serve as the primary source of the Bank’s funding.
A Final Word
This year, Provident proudly celebrates the 70th anniversary of its founding, serving the great city of Riverside and its surrounding communities. As the largest independent community bank headquartered in Riverside County, we are proud of our distinguished history as a trusted provider of banking services. Just as importantly, we are proud of the commitment demonstrated throughout our organization to strengthen the communities we serve through volunteer service, charitable support and community investment. As we look to the year ahead and beyond, I want to assure you that the Board, management team and employees of Provident remain dedicated to carrying forward the Company’s reputation and legacy, just as we have since our founding. We will remain true to our community banking roots and focus on serving the families and small businesses of the Inland Empire. That heritage is central to who we are, and we intend to build on it in the years to come.
154In closing, I want to recognize and thank our employees and Directors for their commitment and service to Provident. Their efforts make our success possible. I also extend my sincere appreciation to our customers, shareholders, and the communities we serve for the confidence you place in us. Our continued success depends on the trust you place in Provident, and we are grateful for the opportunity to serve you.
68Sincerely,
/s/ Craig G. Blunden
Craig G. Blunden
Chairman of the Board of Directors
Financial Highlights
The following tables set forth information concerning the consolidated financial position and results of operations of the Corporation and its subsidiary at the dates and for the periods indicated.
| (In Thousands, Except Per Share Information) | 2026 | 2025 | 2024 | 2023 | 2022 |
|---|---|---|---|---|---|
| FINANCIAL CONDITION DATA: | |||||
| Total assets | $1,208,161 | $1,245,613 | $1,272,200 | $1,332,948 | $1,187,038 |
| Loans held for investment, net | 1,032,682 | 1,045,745 | 1,052,979 | 1,077,629 | 939,992 |
| Cash and cash equivalents | 49,210 | 53,090 | 51,376 | 65,849 | 23,414 |
| Investment securities | 90,523 | 111,006 | 131,900 | 156,492 | 188,421 |
| Deposits | 910,383 | 888,772 | 888,348 | 950,571 | 955,504 |
| Borrowings | 157,046 | 213,073 | 238,500 | 235,009 | 85,000 |
| Stockholders’ equity | 126,220 | 128,545 | 129,941 | 129,687 | 128,650 |
| Book value per share | 20.15 | 19.54 | 18.98 | 18.41 | 17.66 |
| OPERATING DATA: | |||||
| Interest income | $55,889 | $56,624 | $54,730 | $45,992 | $34,730 |
| Interest expense | 19,561 | 21,155 | 19,807 | 9,007 | 3,135 |
| Net interest income | 36,328 | 35,469 | 34,923 | 36,985 | 31,595 |
| (Recovery of) provision for credit losses | (553) | (666) | (63) | 374 | (2,462) |
| Net interest income after (recovery of) provision for credit losses | 36,881 | 36,135 | 34,986 | 36,611 | 34,057 |
| Loan servicing and other fees | 583 | 419 | 337 | 414 | 1,056 |
| Deposit account fees | 1,067 | 1,112 | 1,154 | 1,296 | 1,302 |
| Card and processing fees | 1,203 | 1,265 | 1,384 | 1,525 | 1,639 |
| Other non-interest income | 873 | 735 | 1,066 | 840 | 719 |
| Operating expenses | 30,971 | 30,793 | 28,540 | 28,270 | 25,915 |
| Income before income taxes | 9,636 | 8,873 | 10,387 | 12,416 | 12,858 |
| Provision for income taxes | 2,981 | 2,618 | 3,036 | 3,824 | 3,765 |
| Net income | $6,655 | $6,255 | $7,351 | $8,592 | $9,093 |
| Basic earnings per share | $1.04 | $0.93 | $1.06 | $1.20 | $1.23 |
| Diluted earnings per share | $1.03 | $0.93 | $1.06 | $1.19 | $1.22 |
| Cash dividend per share | $0.56 | $0.56 | $0.56 | $0.56 | $0.56 |
תיקונים בתוך הדוח השנתי, לא שכתוב מודבק
רוב כלי הבינה המלאכותית מחזירים את המכתב כטקסט צ'אט, ומישהו מדביק אותו בחזרה לדוח. עובד בתוך קובץ ה-Word עצמו, משאיר את המספרים והטבלאות בצד, ודוח מעקב השינויים שלו מציג לסקירה כל תיקון ותיקון.
המשיכו לקרוא
קראו דוגמה מעשית נוספת
שיווק ותקשורת
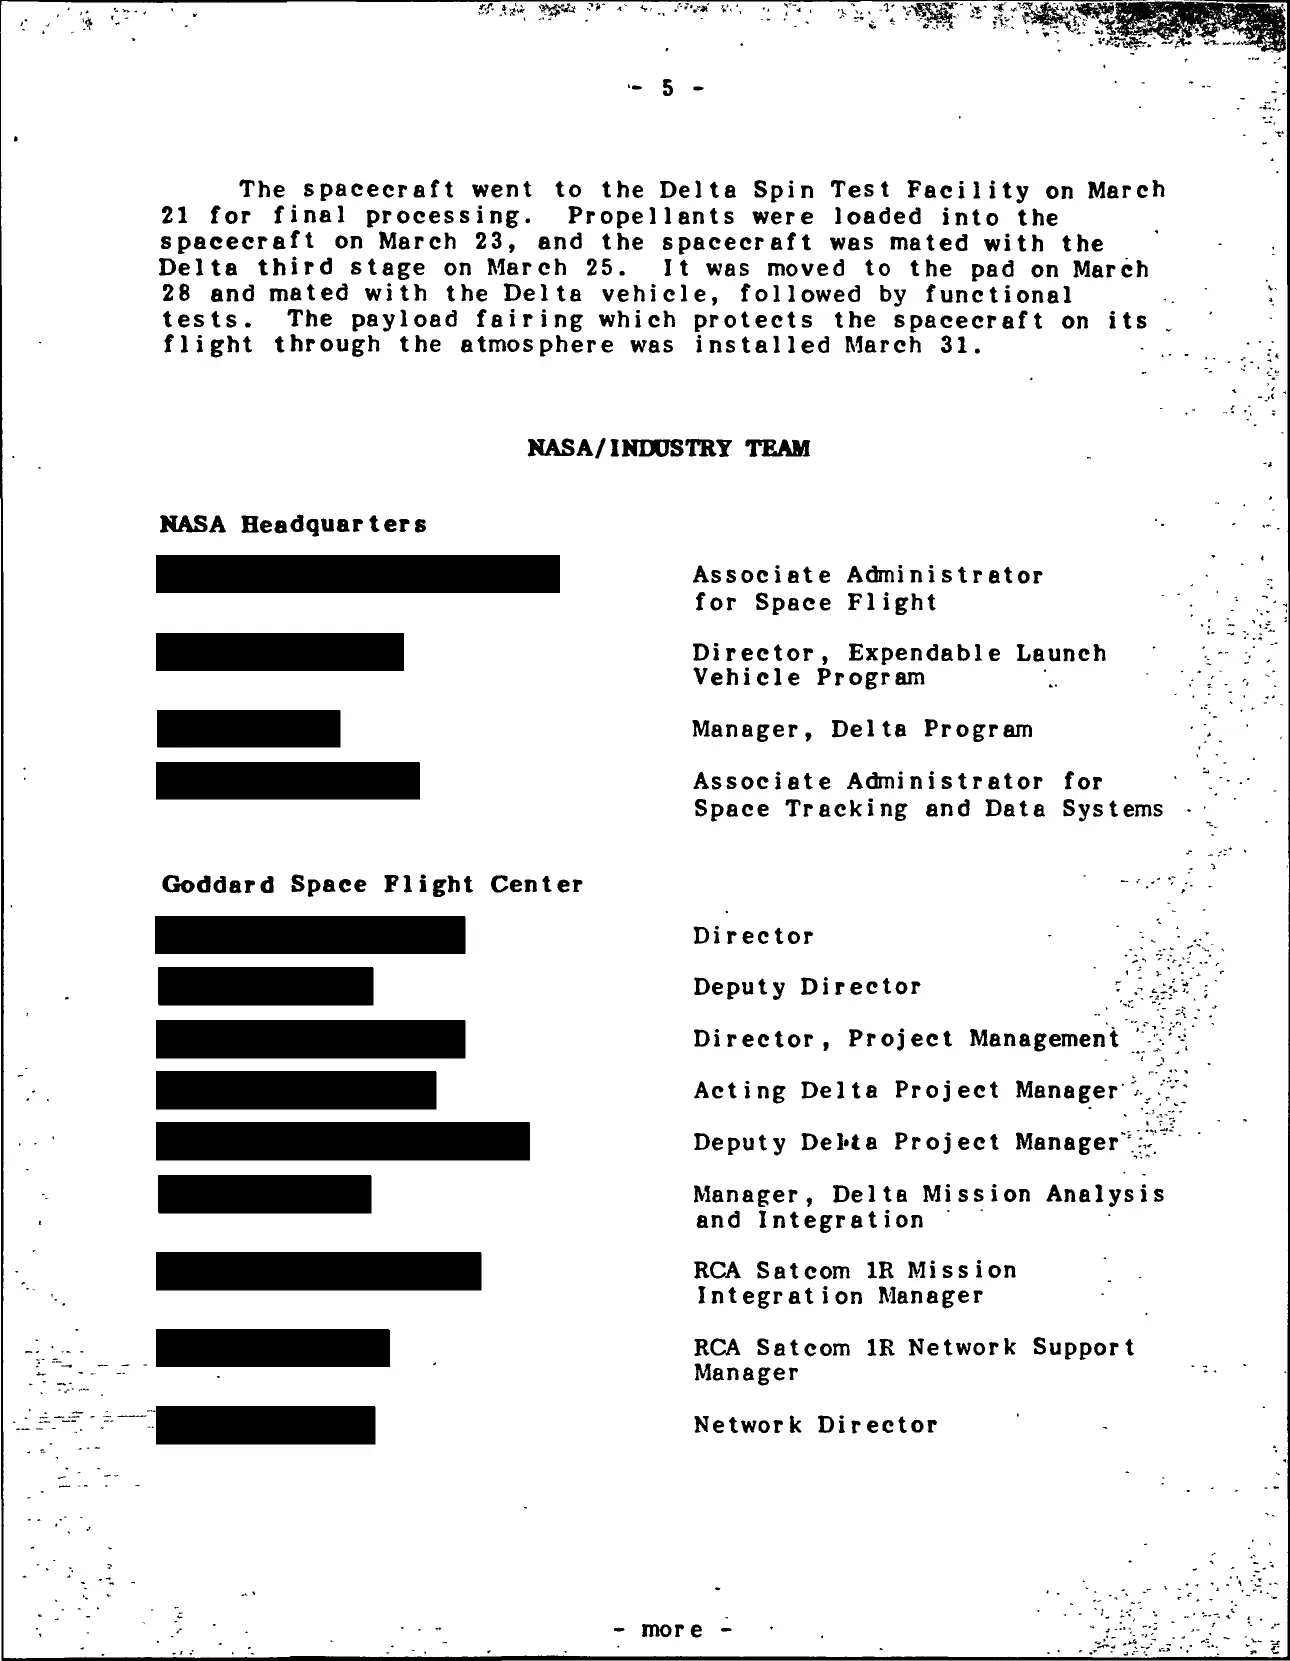
ערכת עיתונות סרוקה של נאס"א מ-1983 עם צנזורה, ולאחר מכן שוחזרה חלקית
בריאות
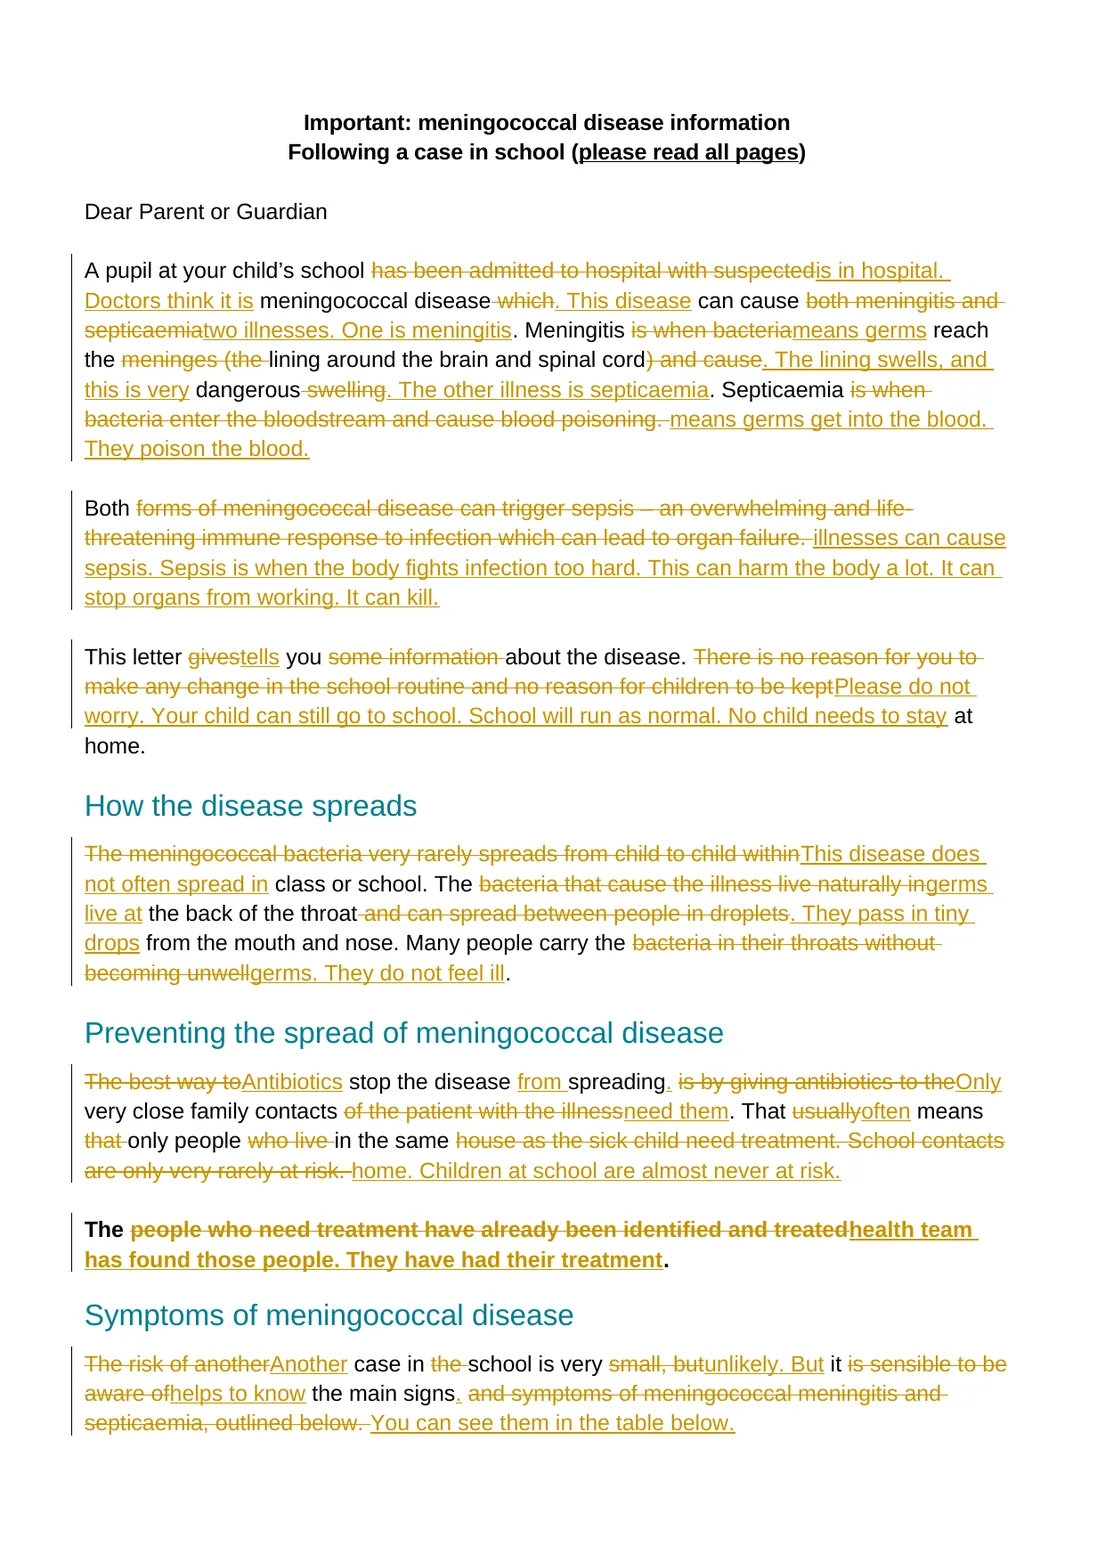
מכתב בריאות להורים פשוט כשינויים במעקב, ולאחר מכן בפולנית
בנקאים ויועצים
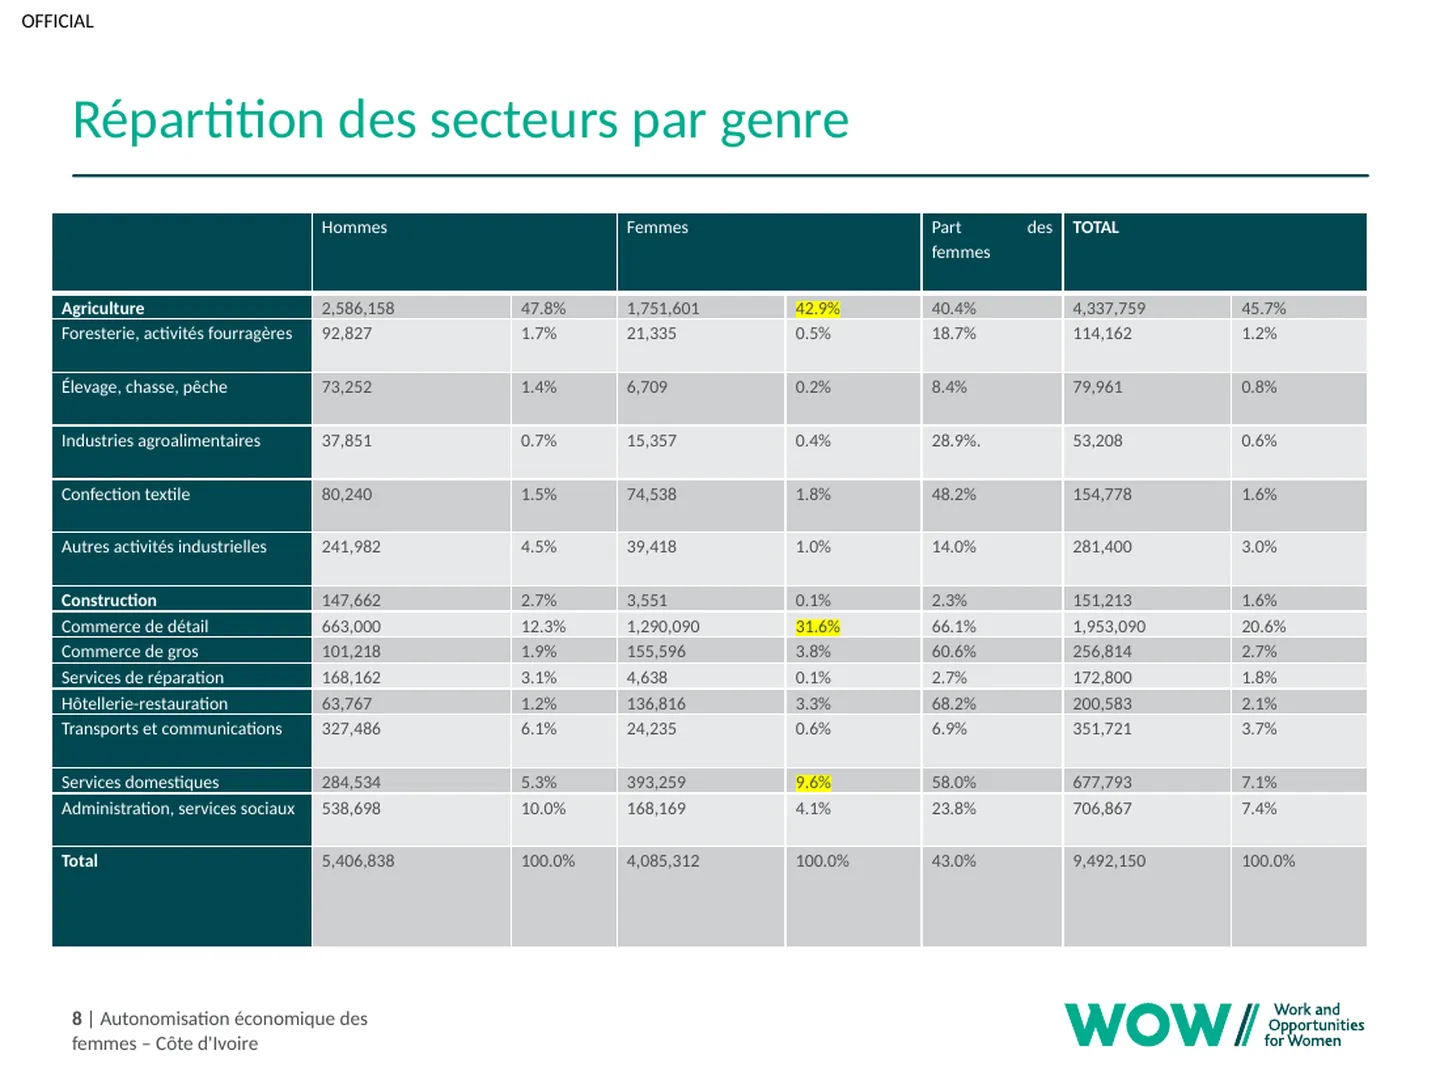
מצגת פיתוח בת 23 שקופיות בצרפתית, ואז שלושה תיקונים
צפו בכל 19 הדוגמאות המעשיות →כל הדוגמאות עבור שיווק ותקשורת →